Freely Corporate Purchasing Card: Business Credit Application & Plaid Linking
Designing a business credit application, multi-owner verification flow, and Plaid bank linking experience.
- 4 Stages
- Progressive Accordion Flow
- 25%+ KYB
- FinCEN Beneficial Ownership
- Plaid + Pave
- Assets & Identity → Alloy UW
1. Turning Business Credit Onboarding into a Clear Conversation
Small-business owners applying for a corporate credit line usually run into a frustrating wall. Halfway through uploading formation documents or listing business owners, traditional bank applications feel like an interrogation—bouncing founders between PDF disclosures, confusing legal terms, and multi-day email threads before they ever find out if they qualify.
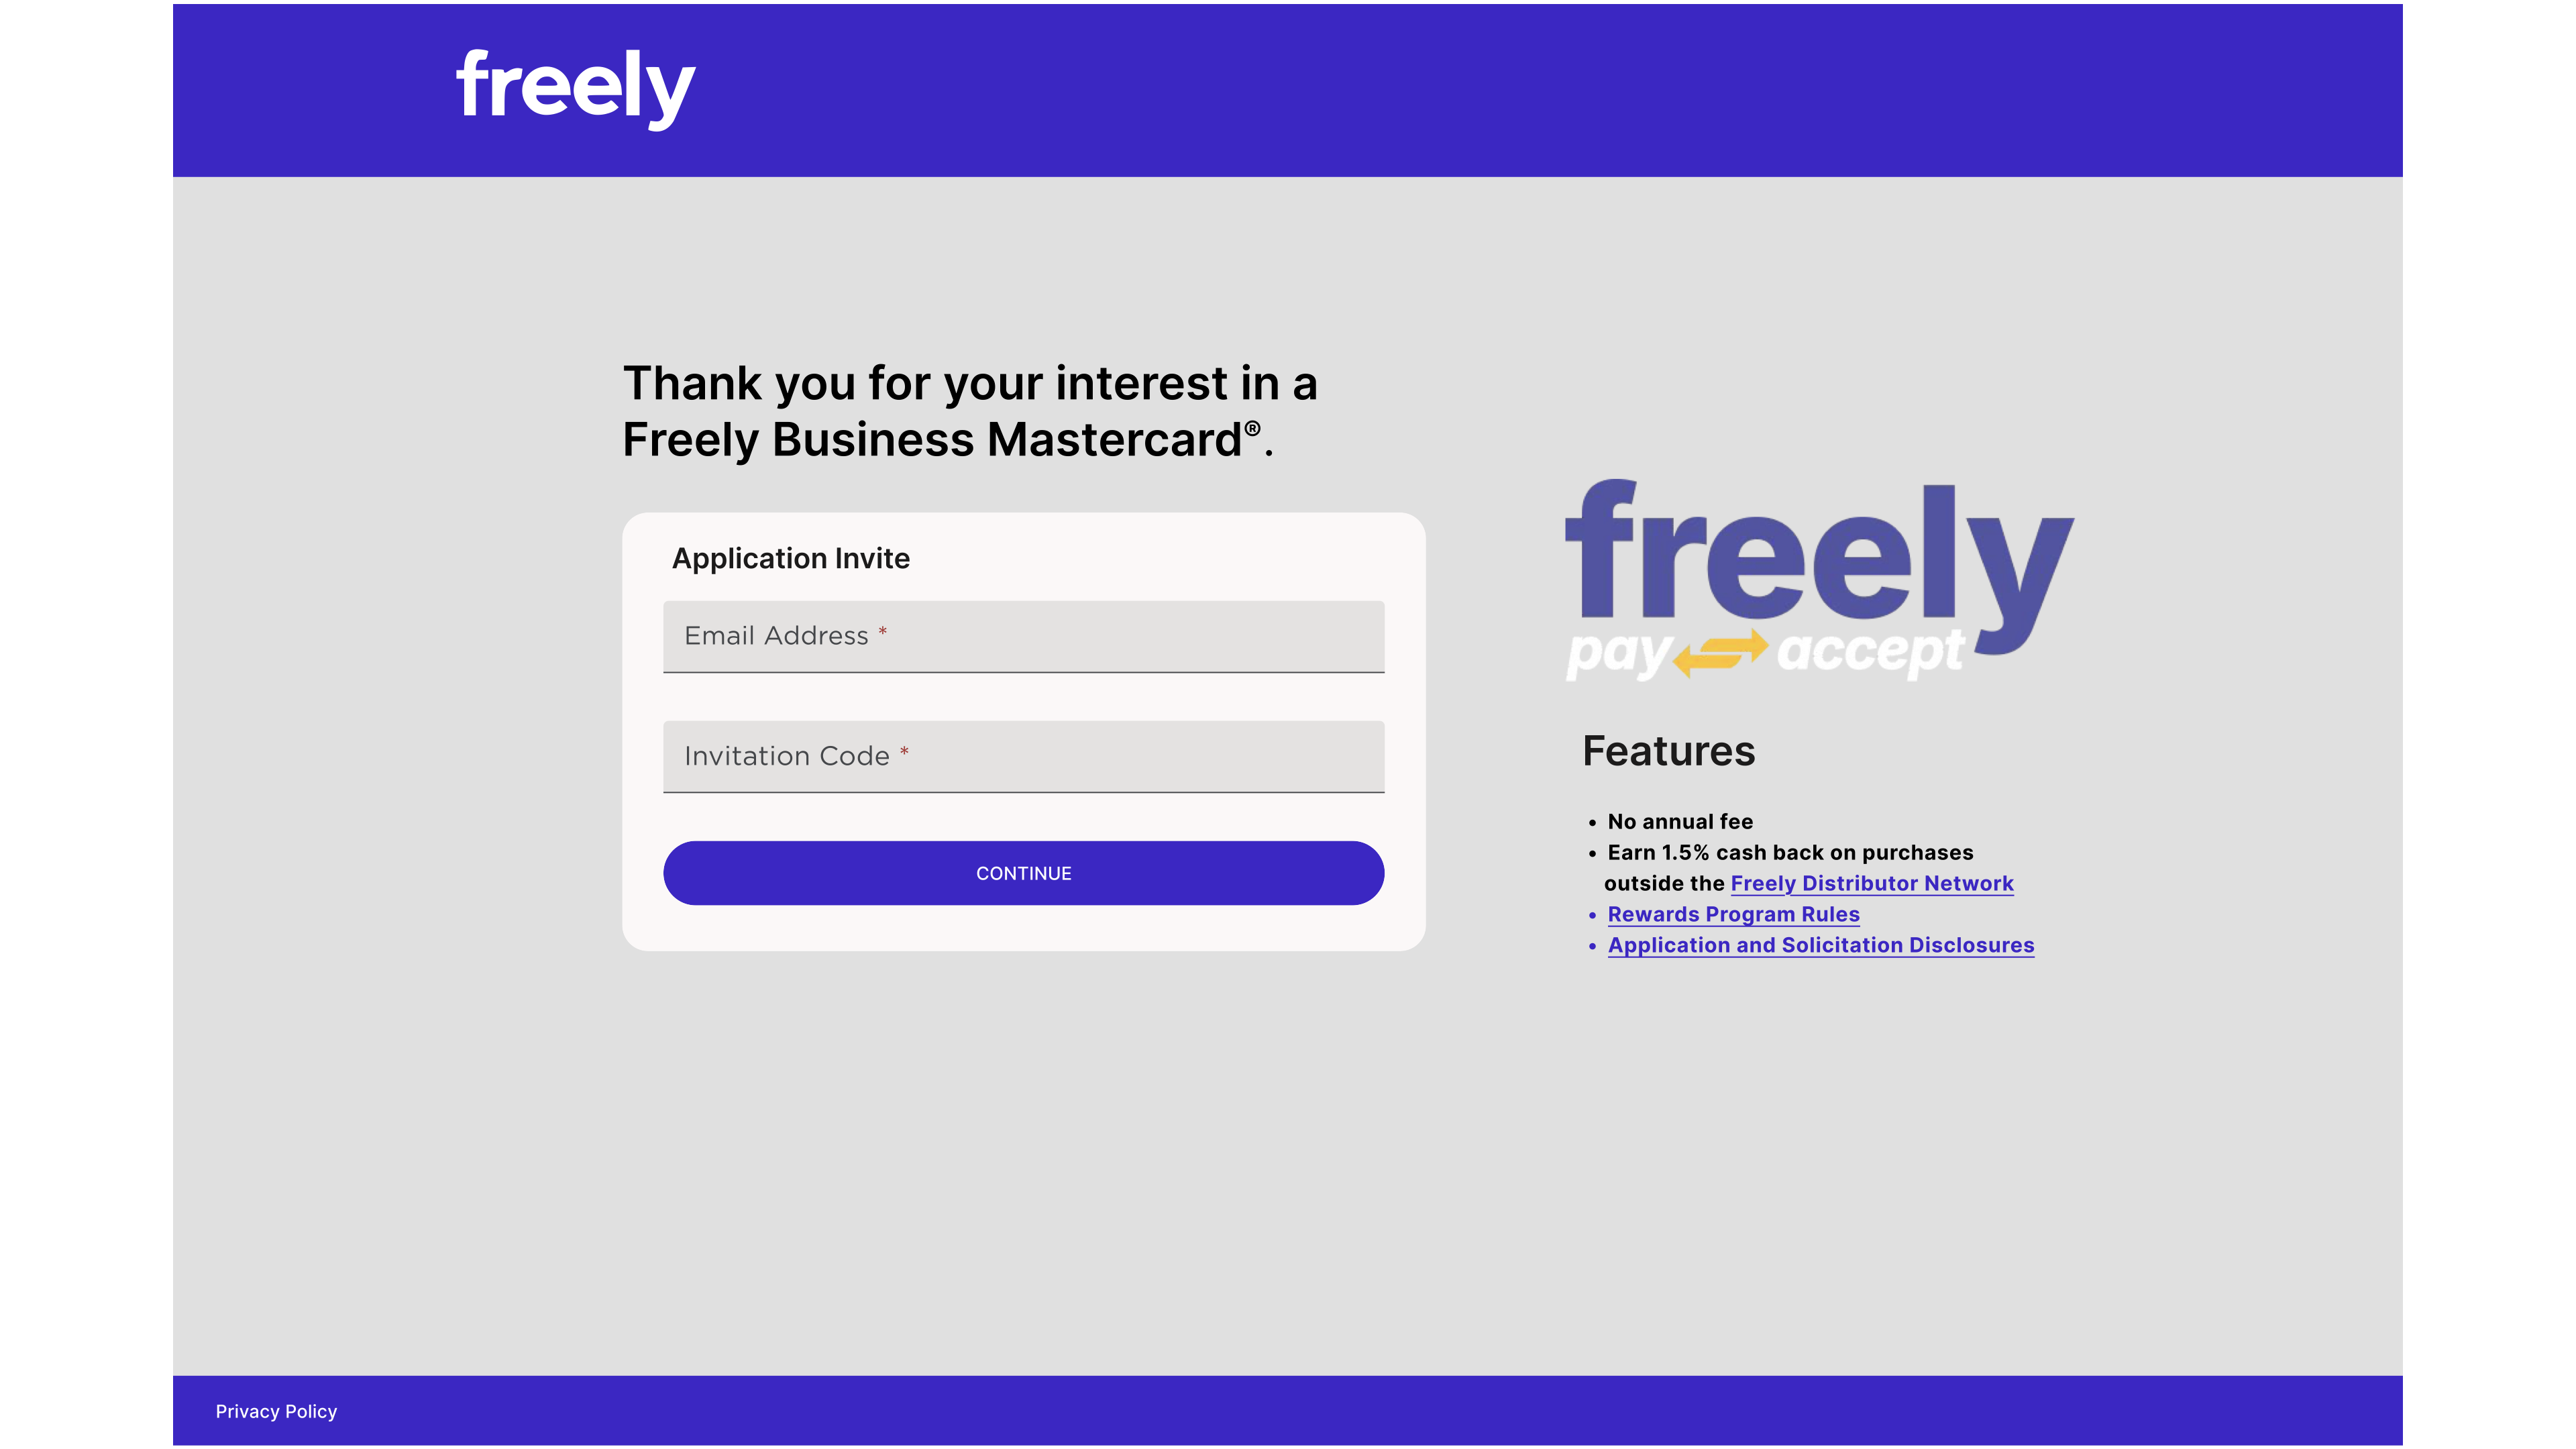
Partnering closely with Freely, our CTO, Risk & Fraud lead, Chief Compliance Officer, and legal counsel, I designed the Freely Corporate Purchasing World Elite Mastercard experience from scratch. Starting from the physical and virtual card art for Freely and its regional foodservice distributor partners, we shaped the web acquisition page, the business credit application, and the Plaid bank-linking flow so that complex regulatory checks—like KYB verification, FinCEN 25%+ beneficial ownership, and Truth in Lending disclosures—feel like a calm, step-by-step conversation with automatic state recovery if an owner needs to step away and finish later.
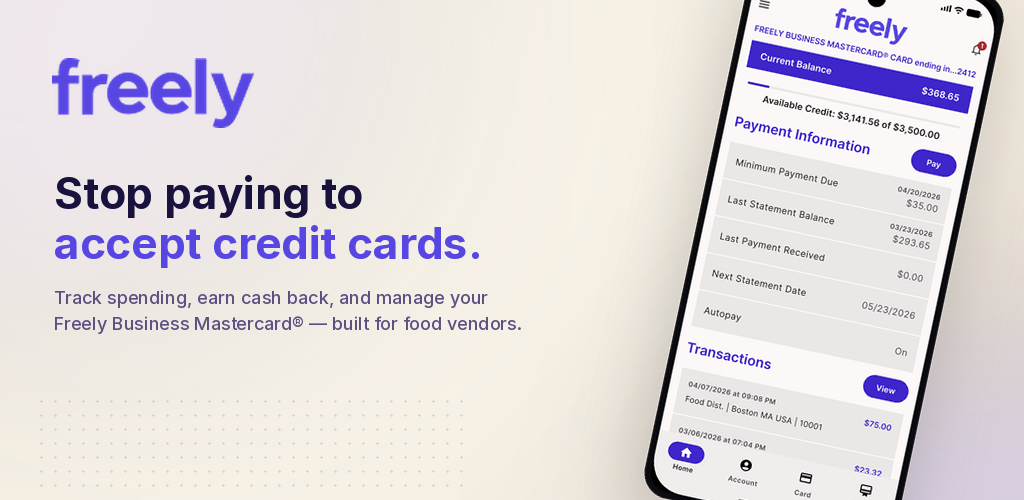
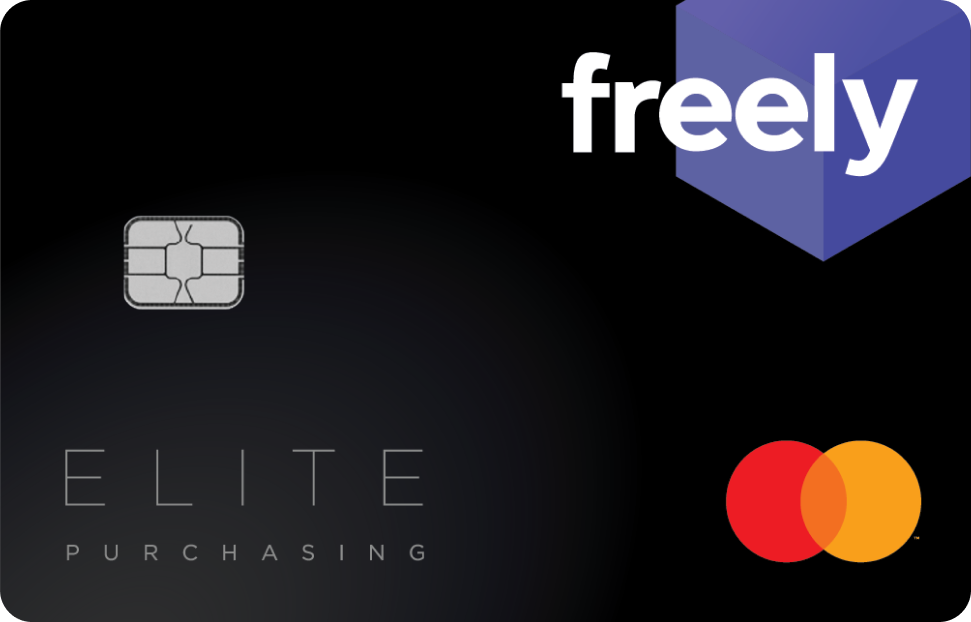
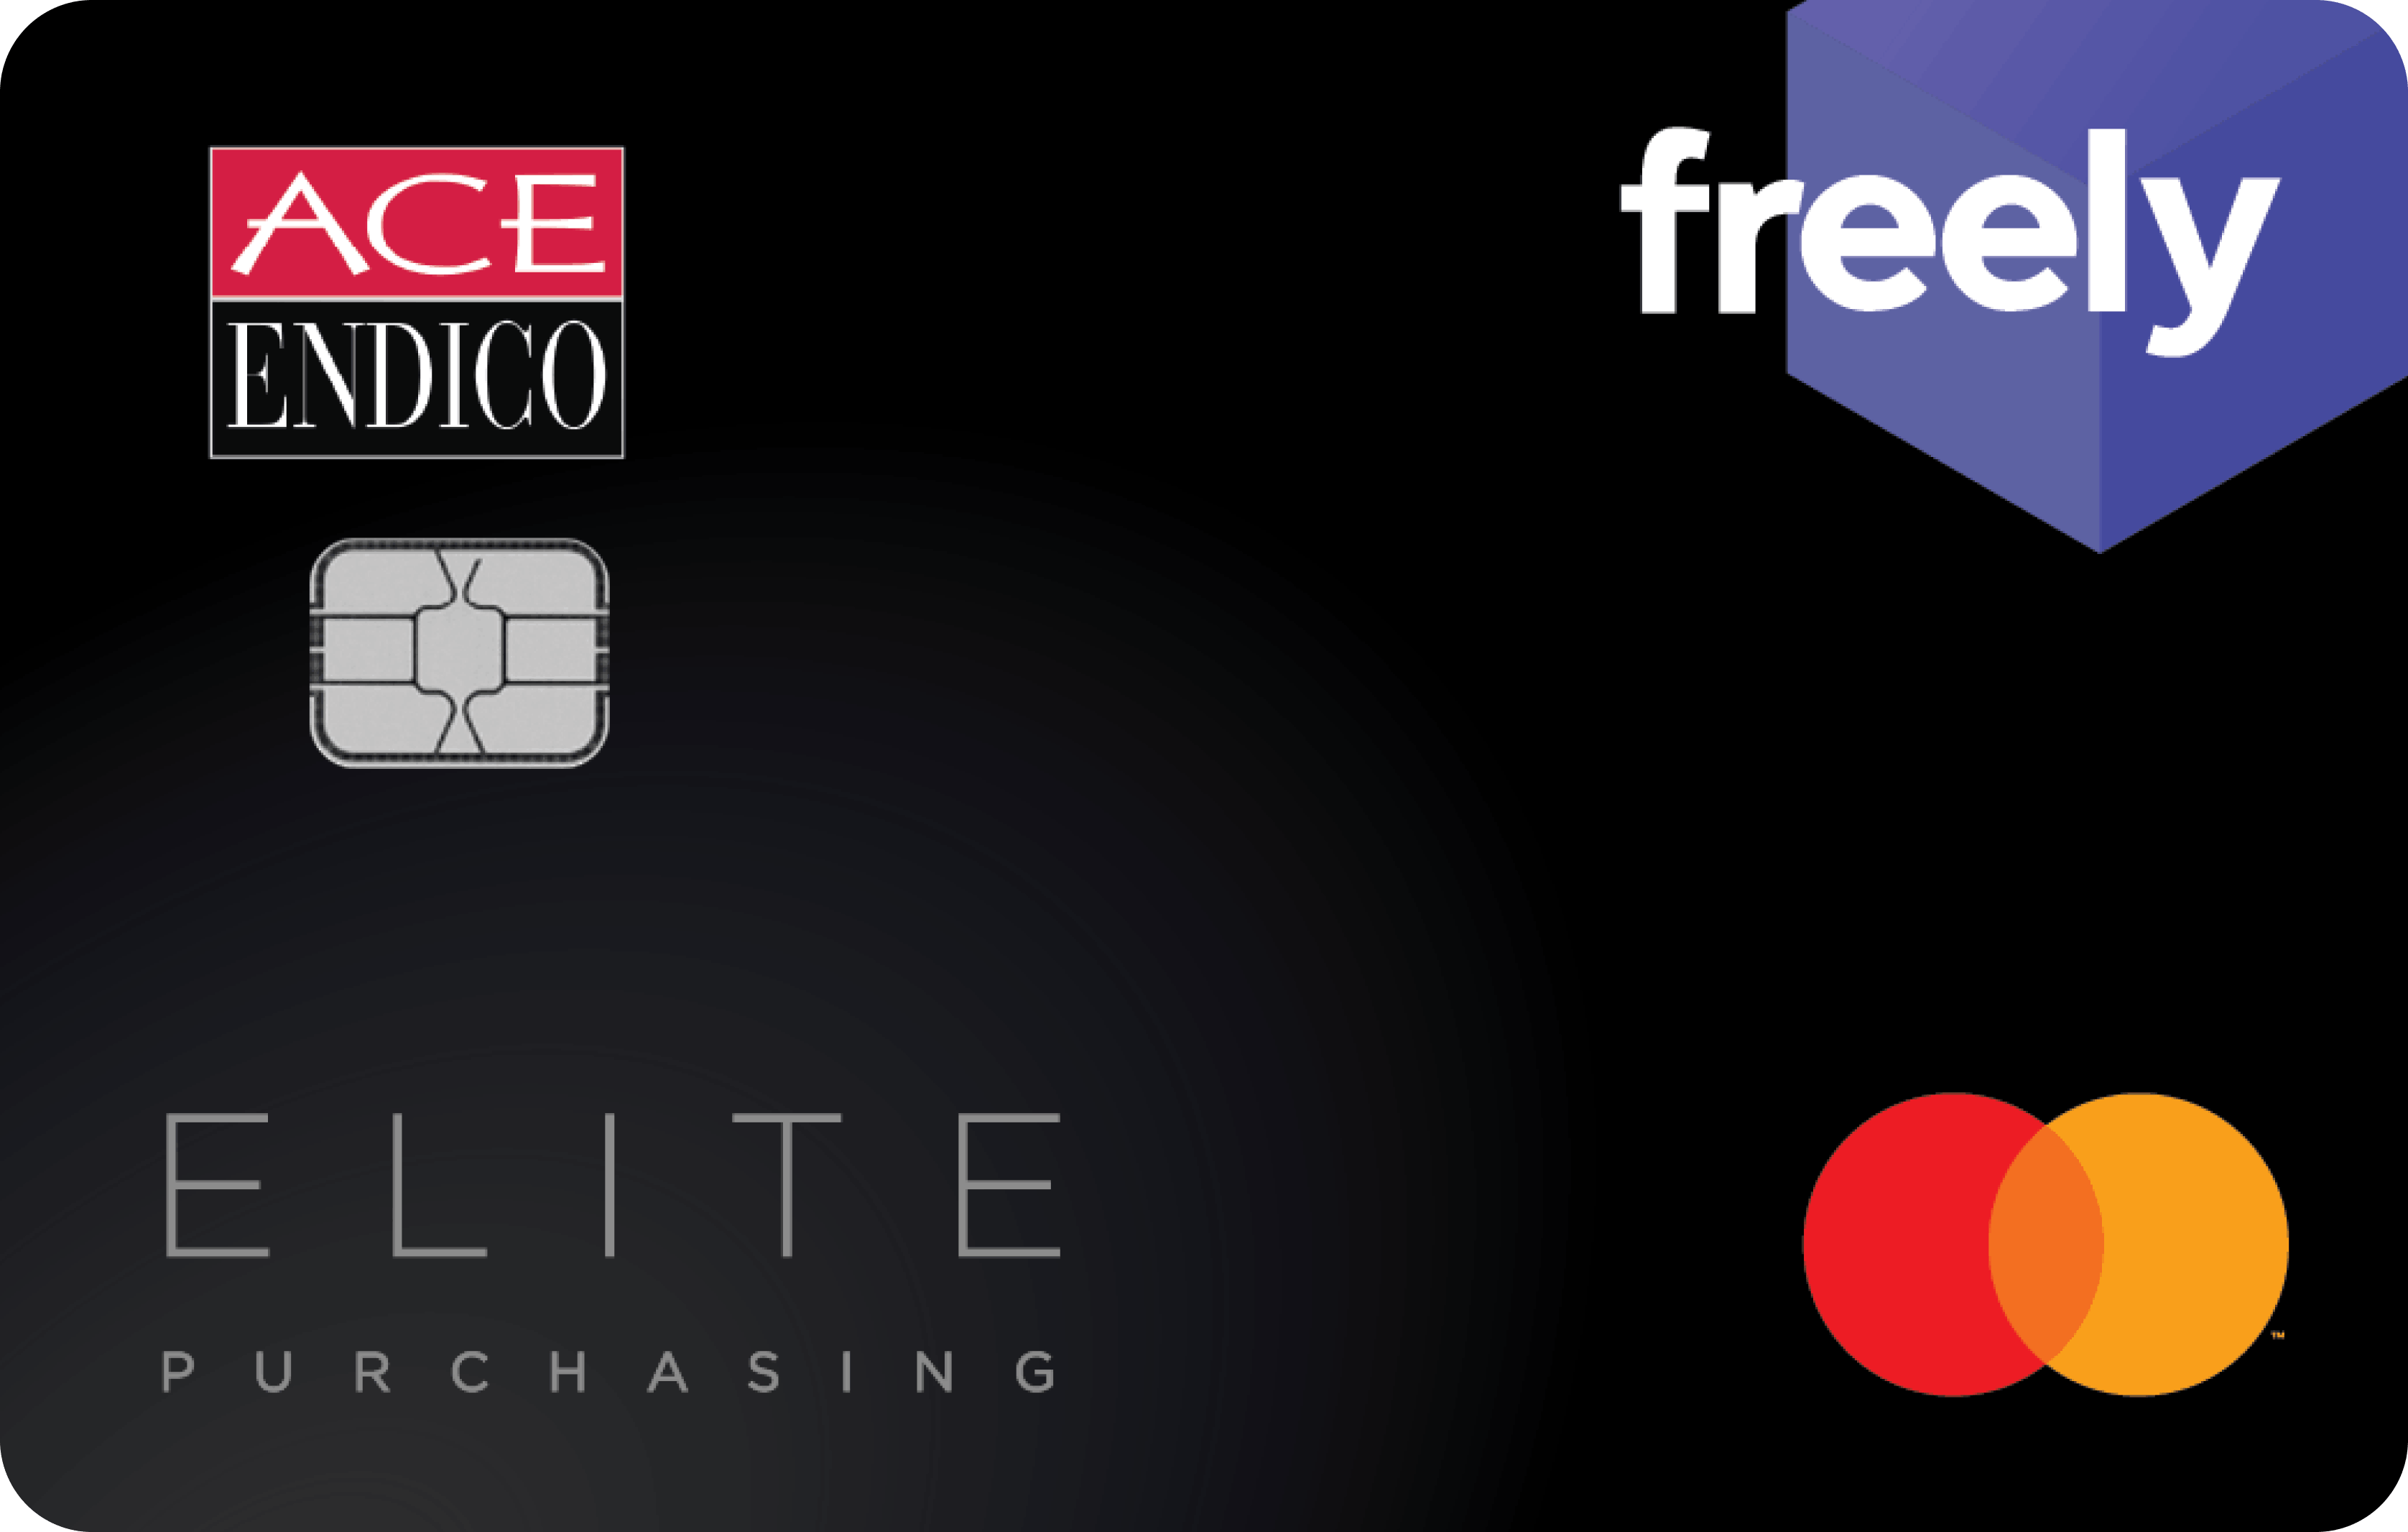
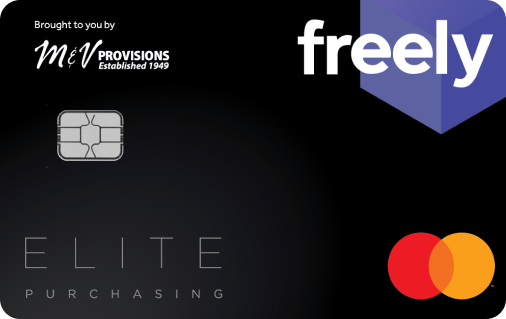
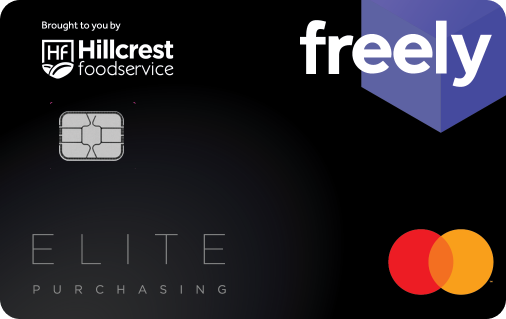
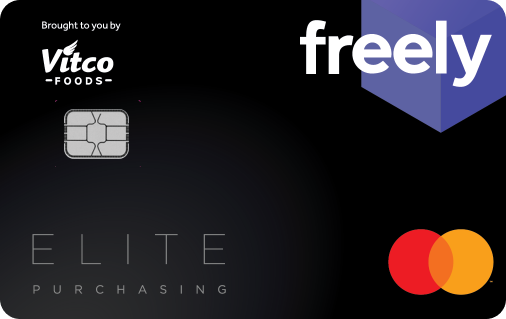
Physical & Virtual Co-Branded Distributor Card Art System
Because Freely partners with regional wholesale food and beverage distributors, I designed a modular co-branded Mastercard art system that supports both the standalone Freely Elite Purchasing virtual/physical card and distributor-co-branded variants—preserving EMV chip clearance, geometric 3D brand lockup, and high-contrast distributor marks (Ace Endico, M&V Provisions, Hillcrest Foodservice, Vitco Foods) across Apple Wallet, Google Wallet, and physical card manufacturing specs.
2. Why Business Credit Applications Are Hard to Design
Unlike a personal credit card—where one person verifies their own identity—a business credit card application has to verify both a legal company and multiple people inside it:
- The person applying isn't always the owner: An office manager or CFO might start the application, while a majority owner has to sign the personal guarantee.
- Beneficial ownership rules: Federal banking rules (FinCEN 31 CFR § 1010.230) require collecting full identity details (Name, DOB, Home Address, SSN/ITIN) for every person who owns 25% or more of the company, plus a Controlling Officer.
- Mid-application interruptions: Connecting a business bank account through Plaid is where most business applications stall—someone doesn't have the bank login handy, or the two-factor code goes to a co-founder's phone.
Our Design Principle
"Never let a business owner get 15 steps into the form only to get stuck because they don't have a co-founder's SSN or bank login ready. Tell them what they need before they start, group the 39 states into four clear stages, and save their progress if they have to step away."
3. Setting Expectations Before Step One
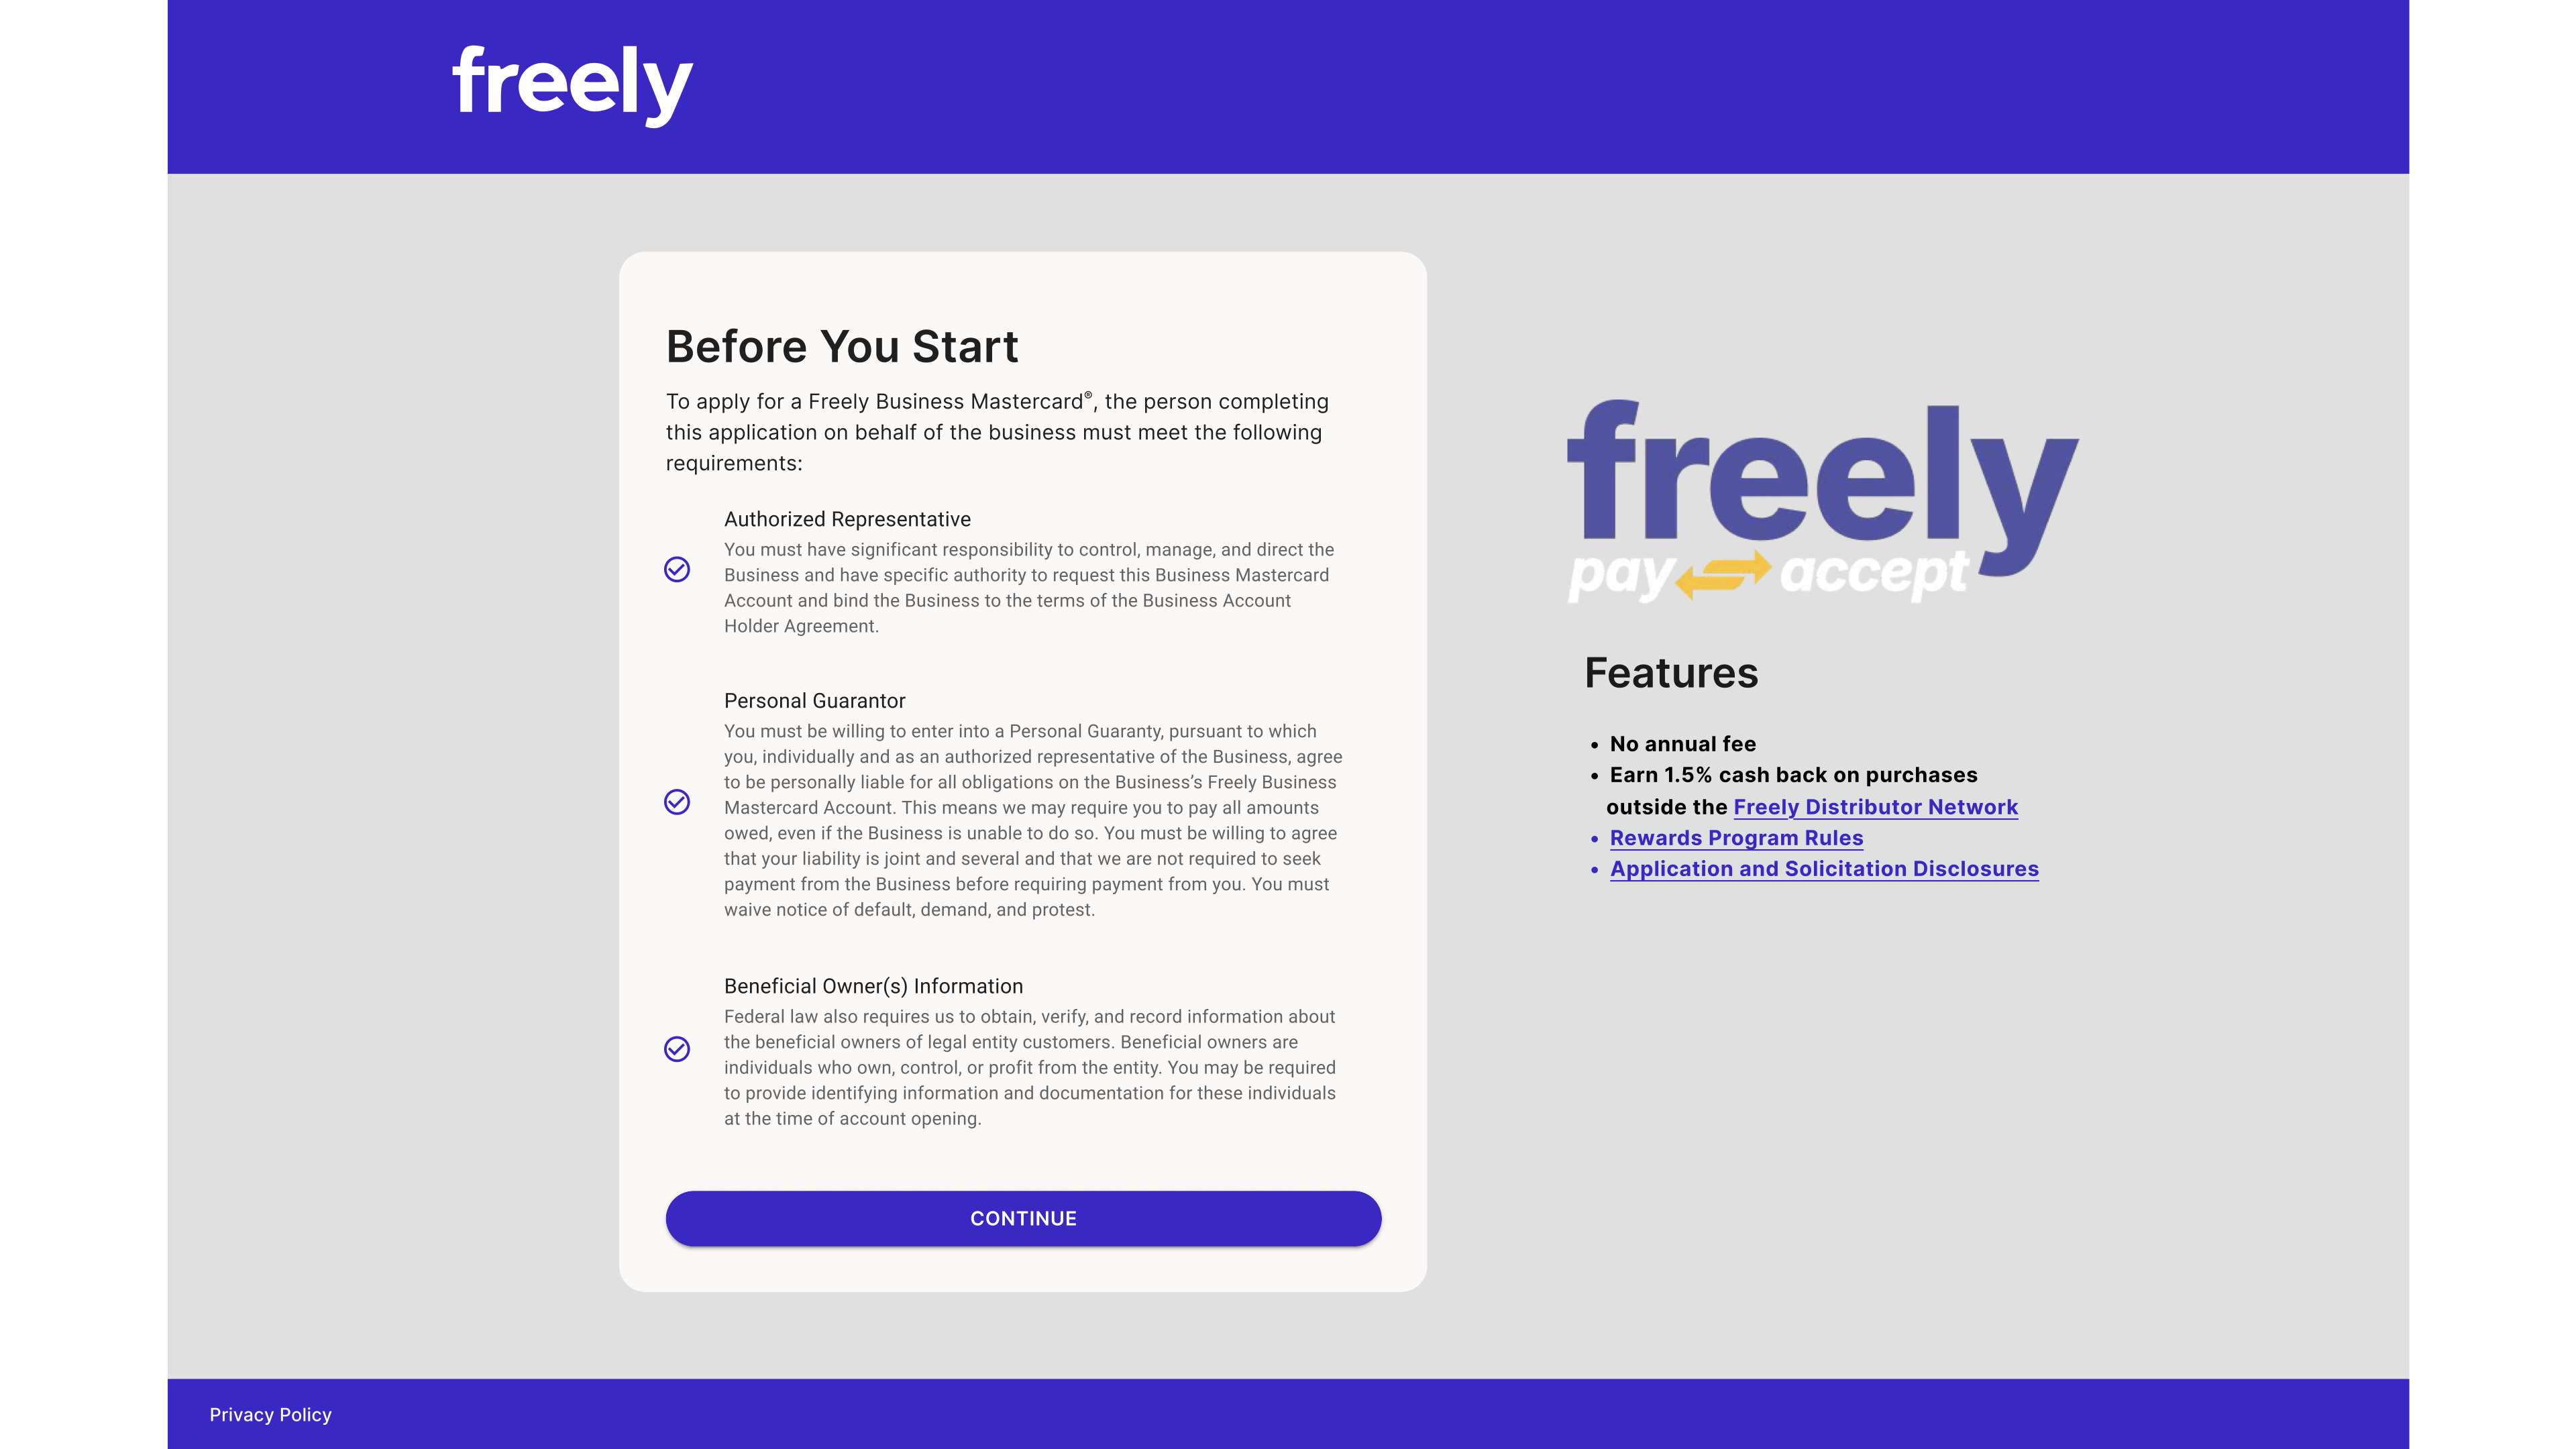
Working with our Chief Compliance Officer, I designed a Before You Start screen that translates legal banking definitions into plain English before the applicant types a single character:
- Authorized Representative: The person authorized to apply on behalf of the business.
- Personal Guarantor: The majority owner (
≥51%) guaranteeing the credit line. - Controlling Officer: An executive (
CEO, CFO, COO, President) who manages the company. - Beneficial Owners: Any co-owners holding
25% or moreof the company.
4. Grouping 39 Screens into 4 Clear Stages
Instead of making applicants click through 39 separate pages, we organized the entire application into a 4-stage accordion flow:
Stages 1–3: Guarantor, Business Details & Co-Owners
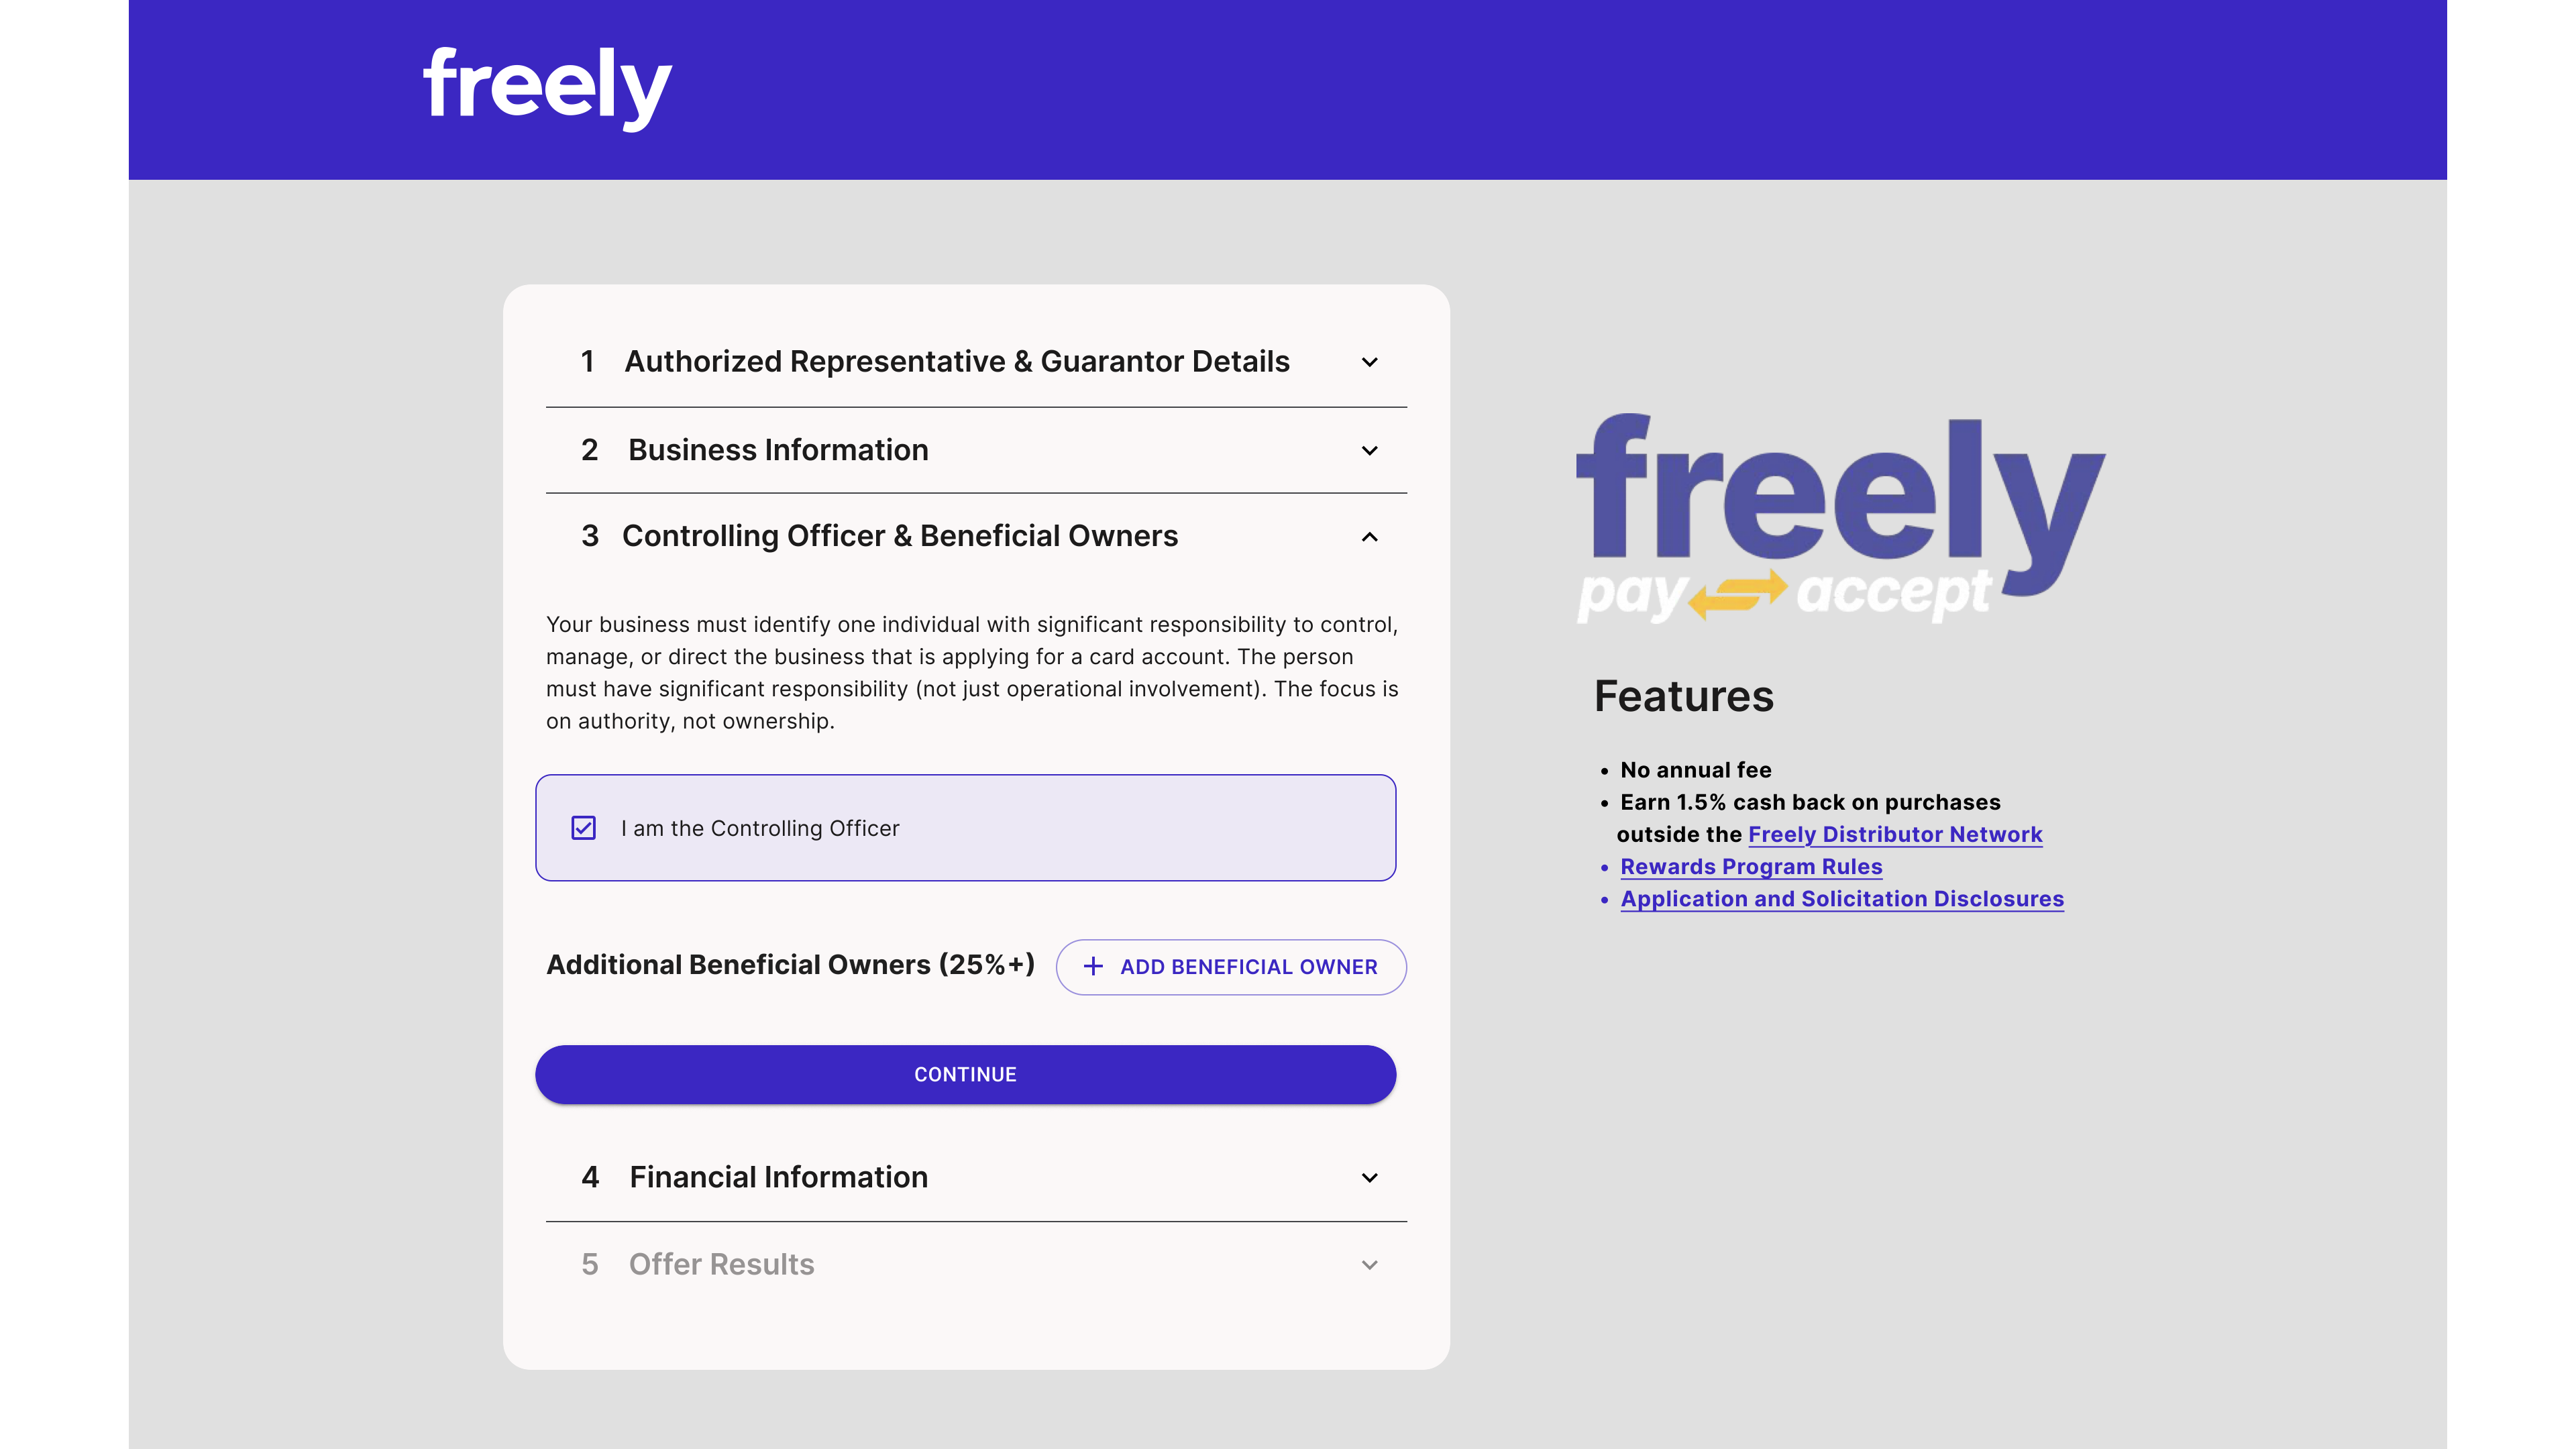
- Avoiding duplicate typing: In most small businesses, the Personal Guarantor is also the Controlling Officer. We added a simple checkbox (
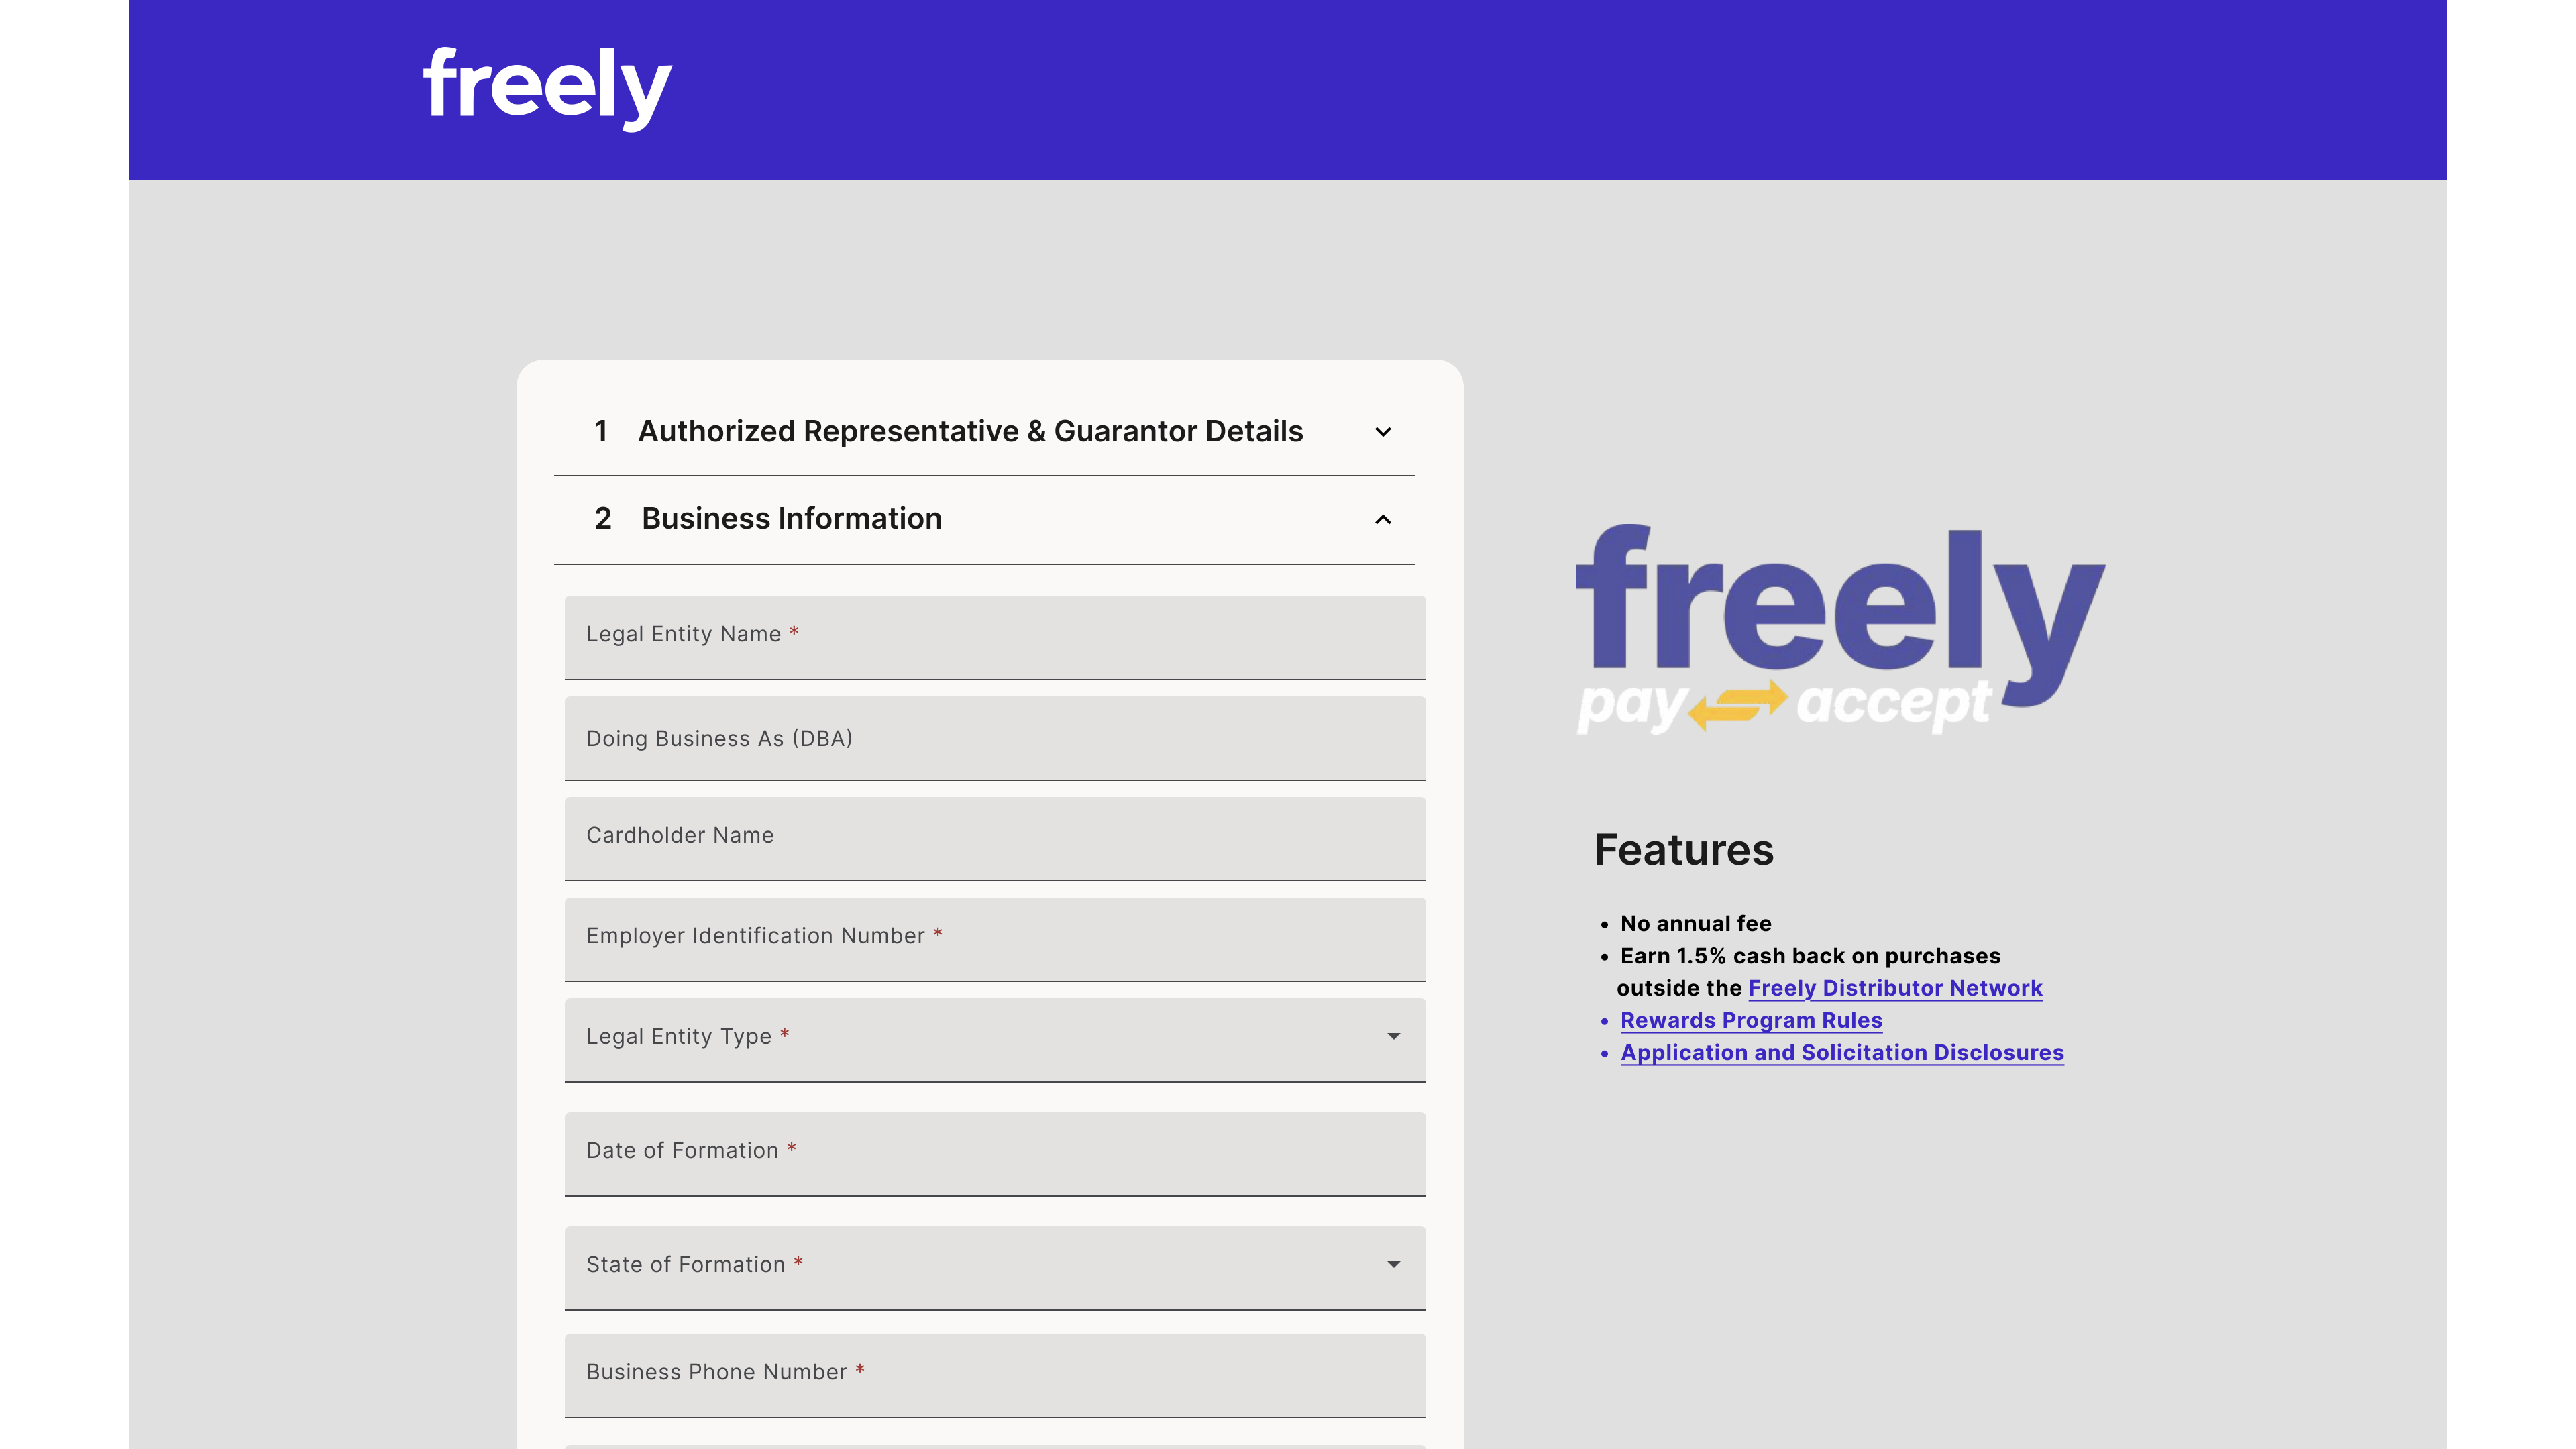
Check here if the Personal Guarantor is also a Controlling Officer) that automatically fills in their officer details in Stage 3 so they never have to type their SSN, birth date, and home address twice. - Business verification: Collects the legal business name, DBA, EIN, company structure (LLC, C-Corp, S-Corp), and industry category.
5. Cash-Flow Underwriting Pipeline (Plaid Assets + Identity → Pave → Alloy UW) & Mid-Flow Recovery
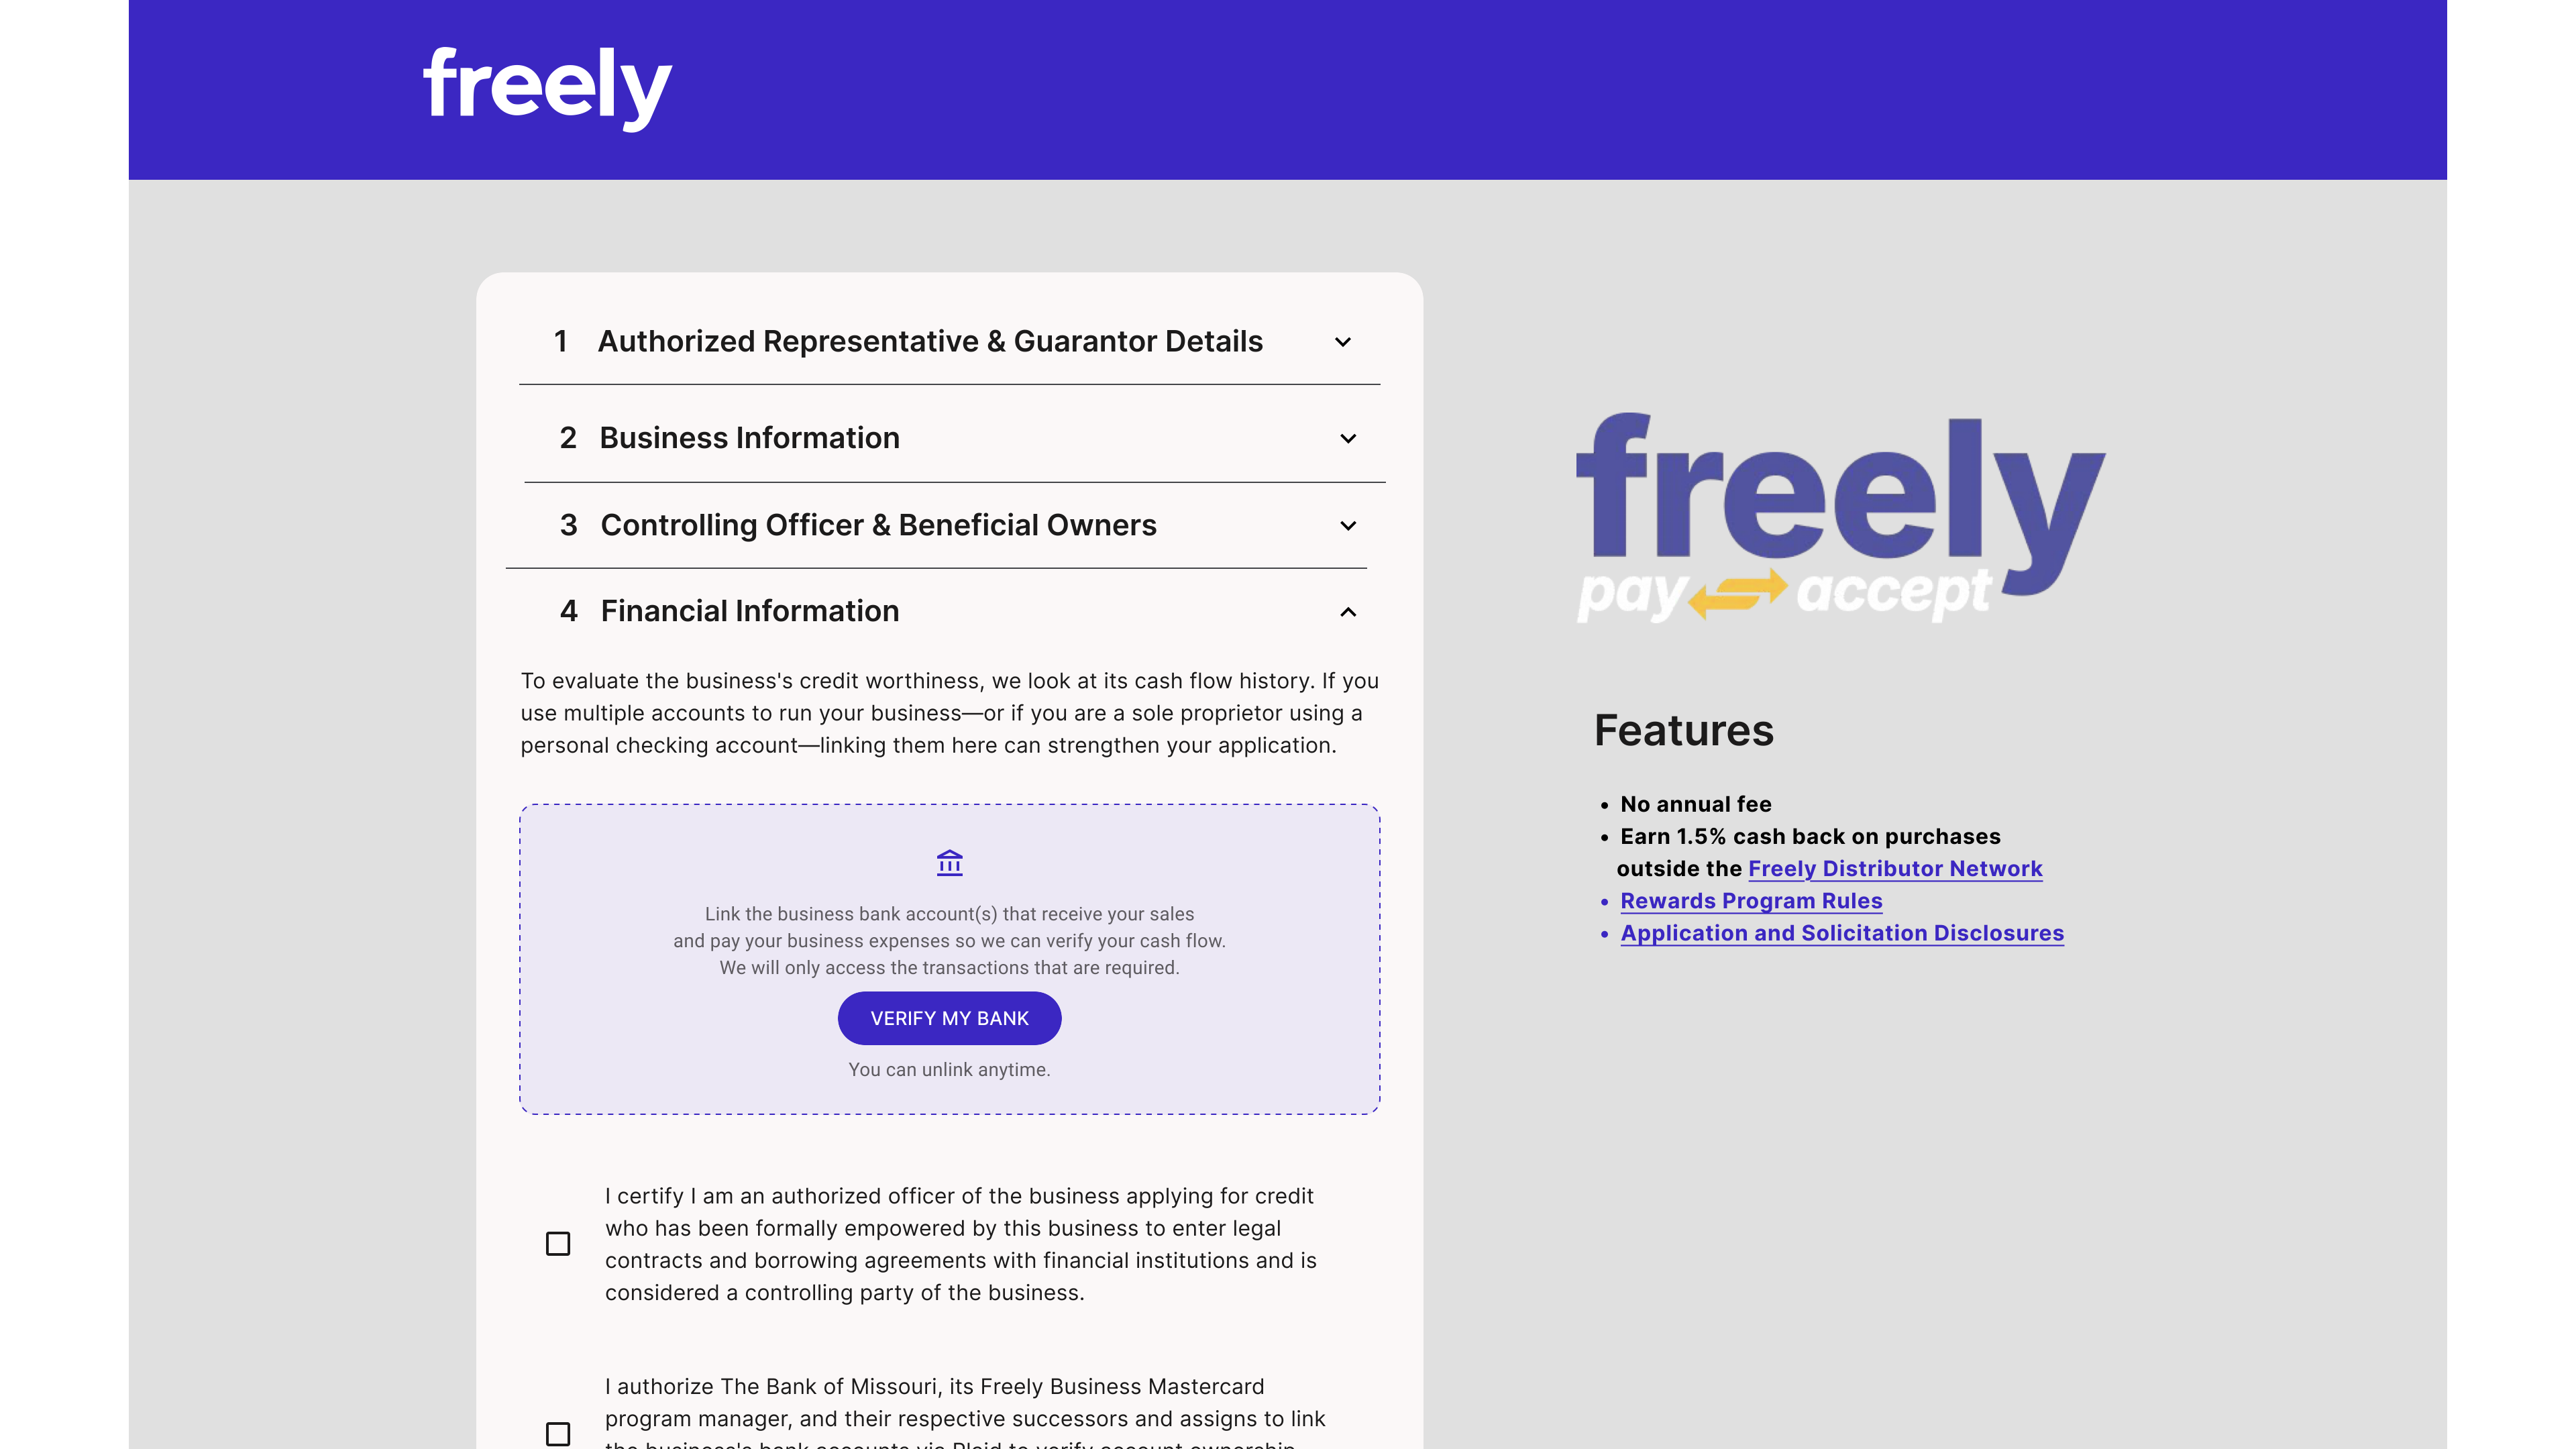
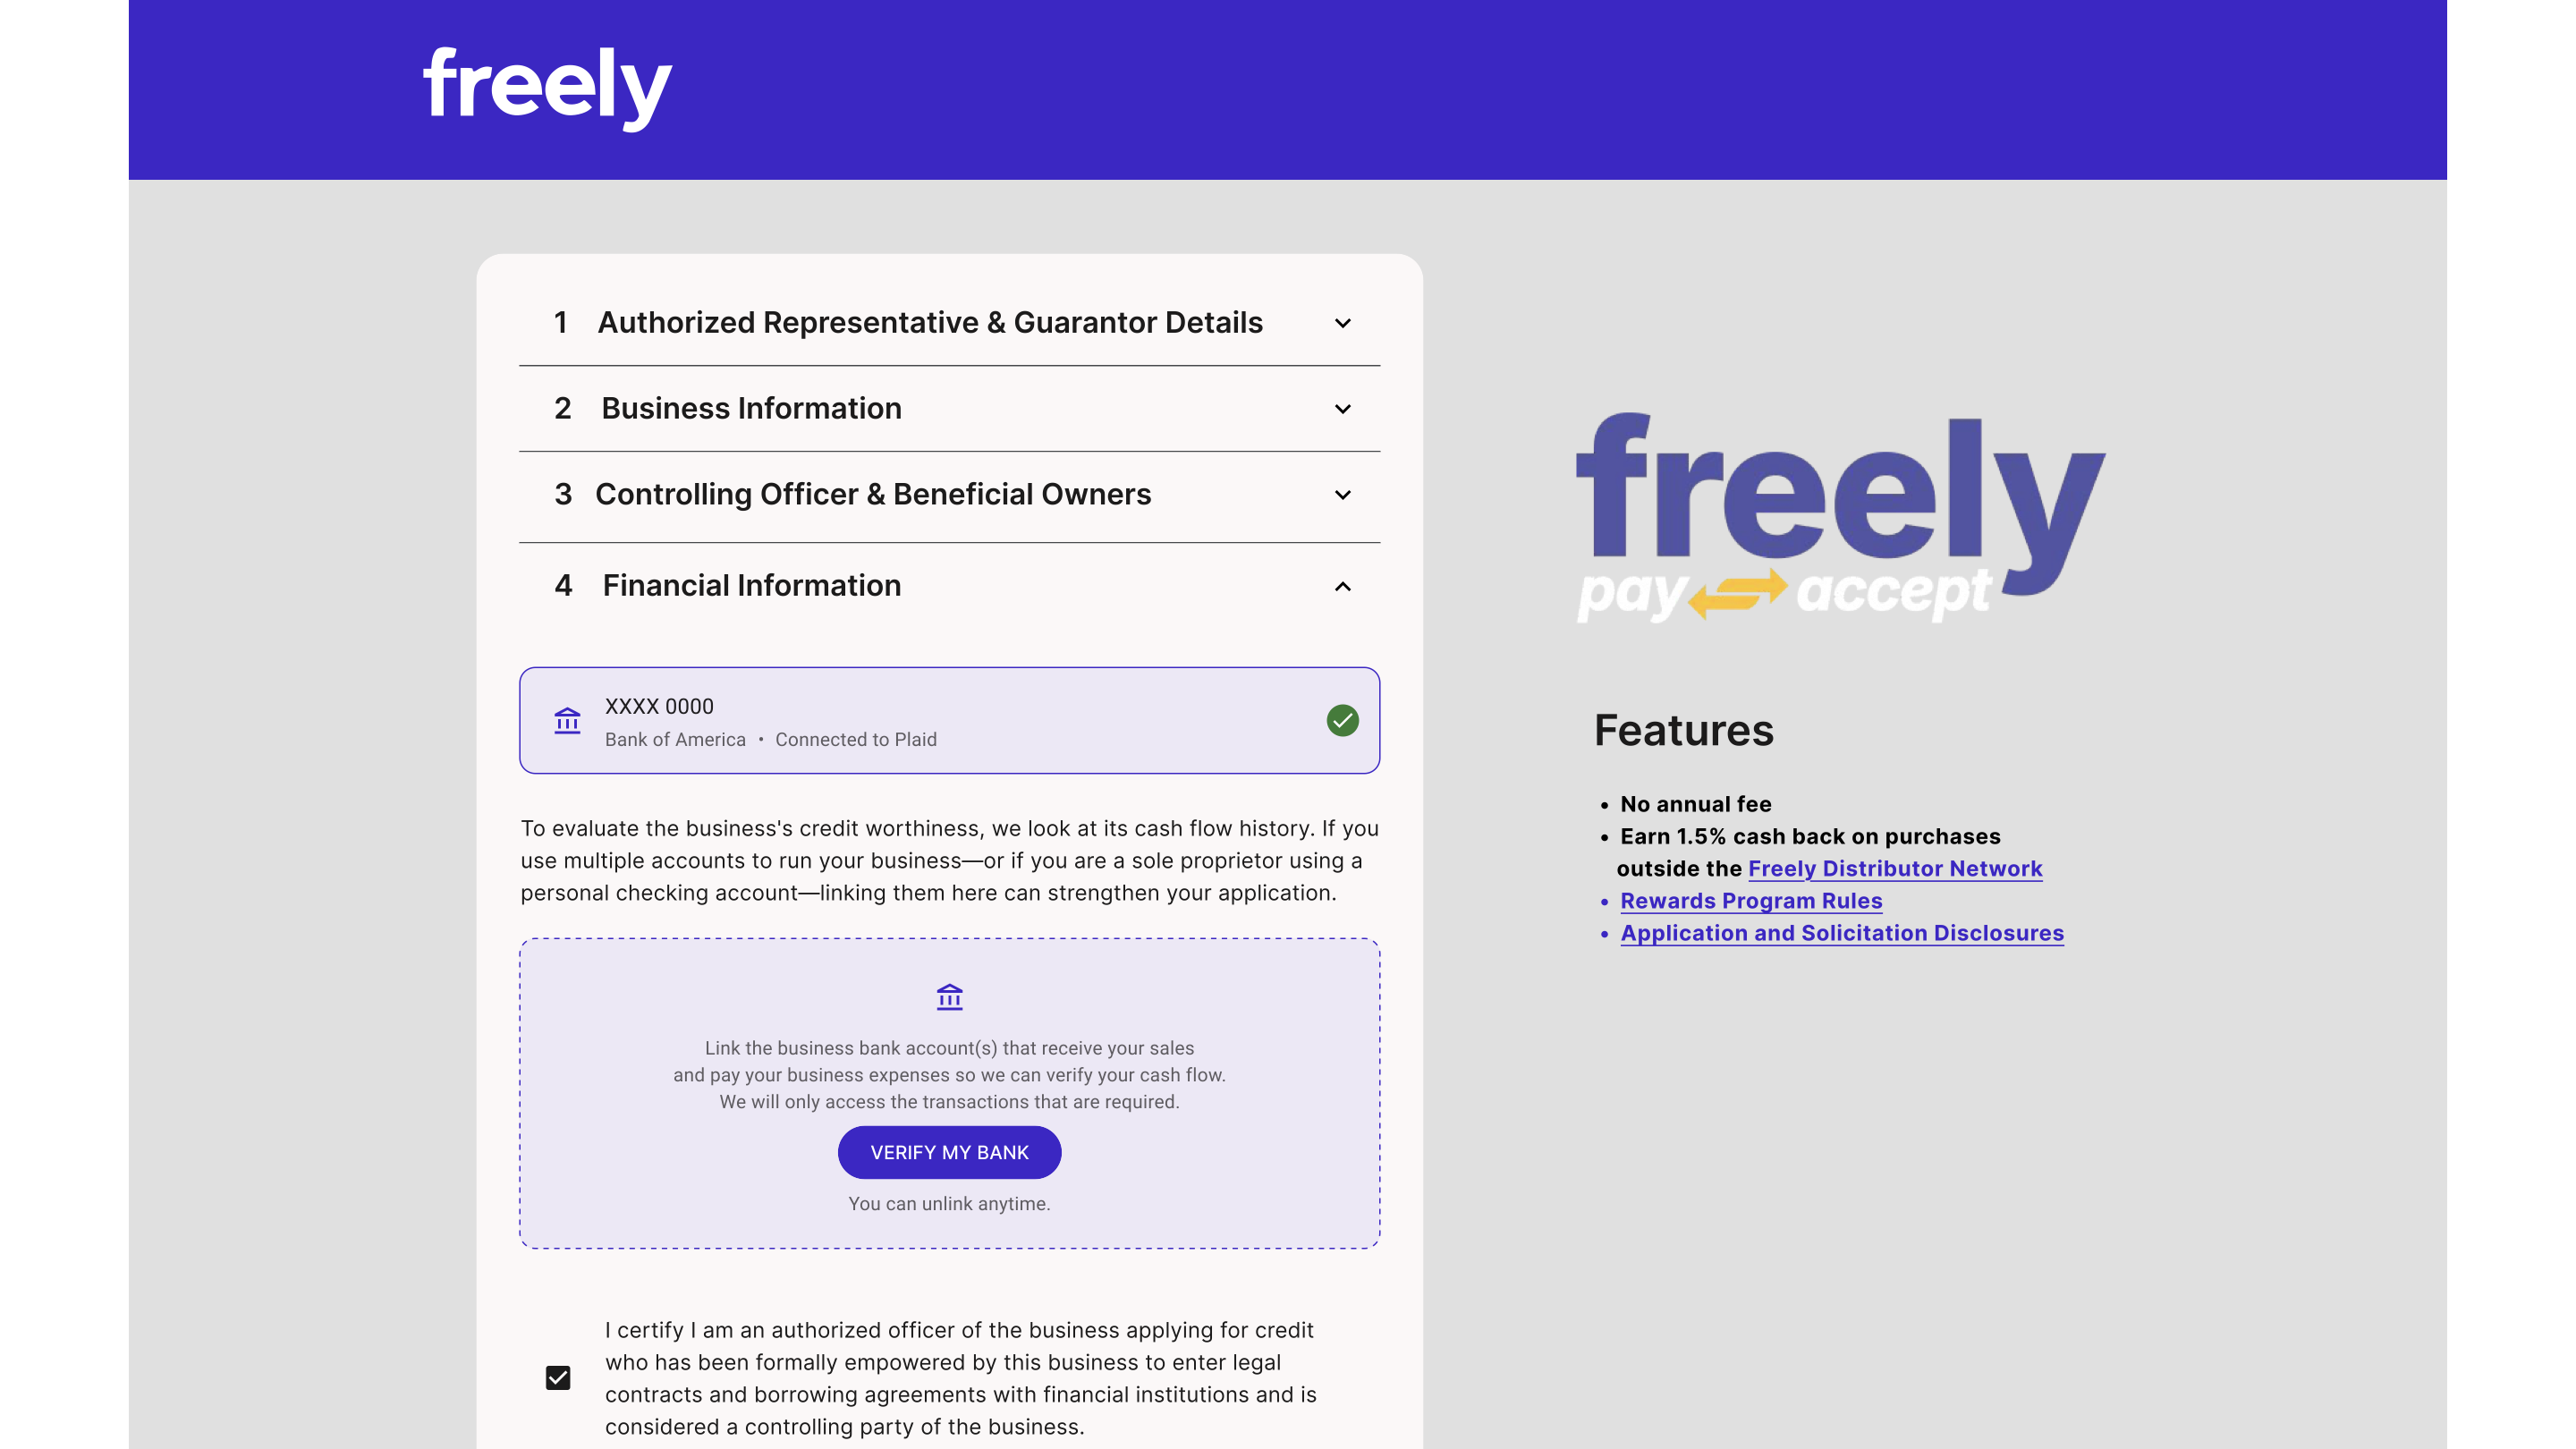
In Stage 4 (Financial Information), we collect annual revenue, estimated monthly card spend, and a connected business bank account via Plaid to power real-time commercial cash-flow underwriting:
- Consistent Identity + Commercial Asset Verification (
Plaid Identity+Plaid Assets): Since we already run Plaid Identity in production on our SIG Sauer VISA program, we stayed architecturally consistent on Freely by pairing Plaid Identity with Plaid Assets to pull verified commercial bank balances and historical cash-flow statements. - Pre-Alloy Attribute Aggregation via
Pave(Plaid Assets → Pave → Alloy UW): Before calling Alloy for credit decisioning, our backend service sends the Plaid Assets payload to Pave, which aggregates raw bank transactions and balance history into standardized cash-flow underwriting attributes. We then pass those enriched Pave attributes directly into Alloy Underwriting (Alloy UW) alongside our The Bank of Missouri (TBOM) sponsor-bank compliance rules.
Designing for real-world interruptions
Bank linking is where business applications fall apart. The person filling out the form often needs a co-founder's login or 2FA code. If they close the Plaid window, we can't afford to lose the 30 fields they already filled out.
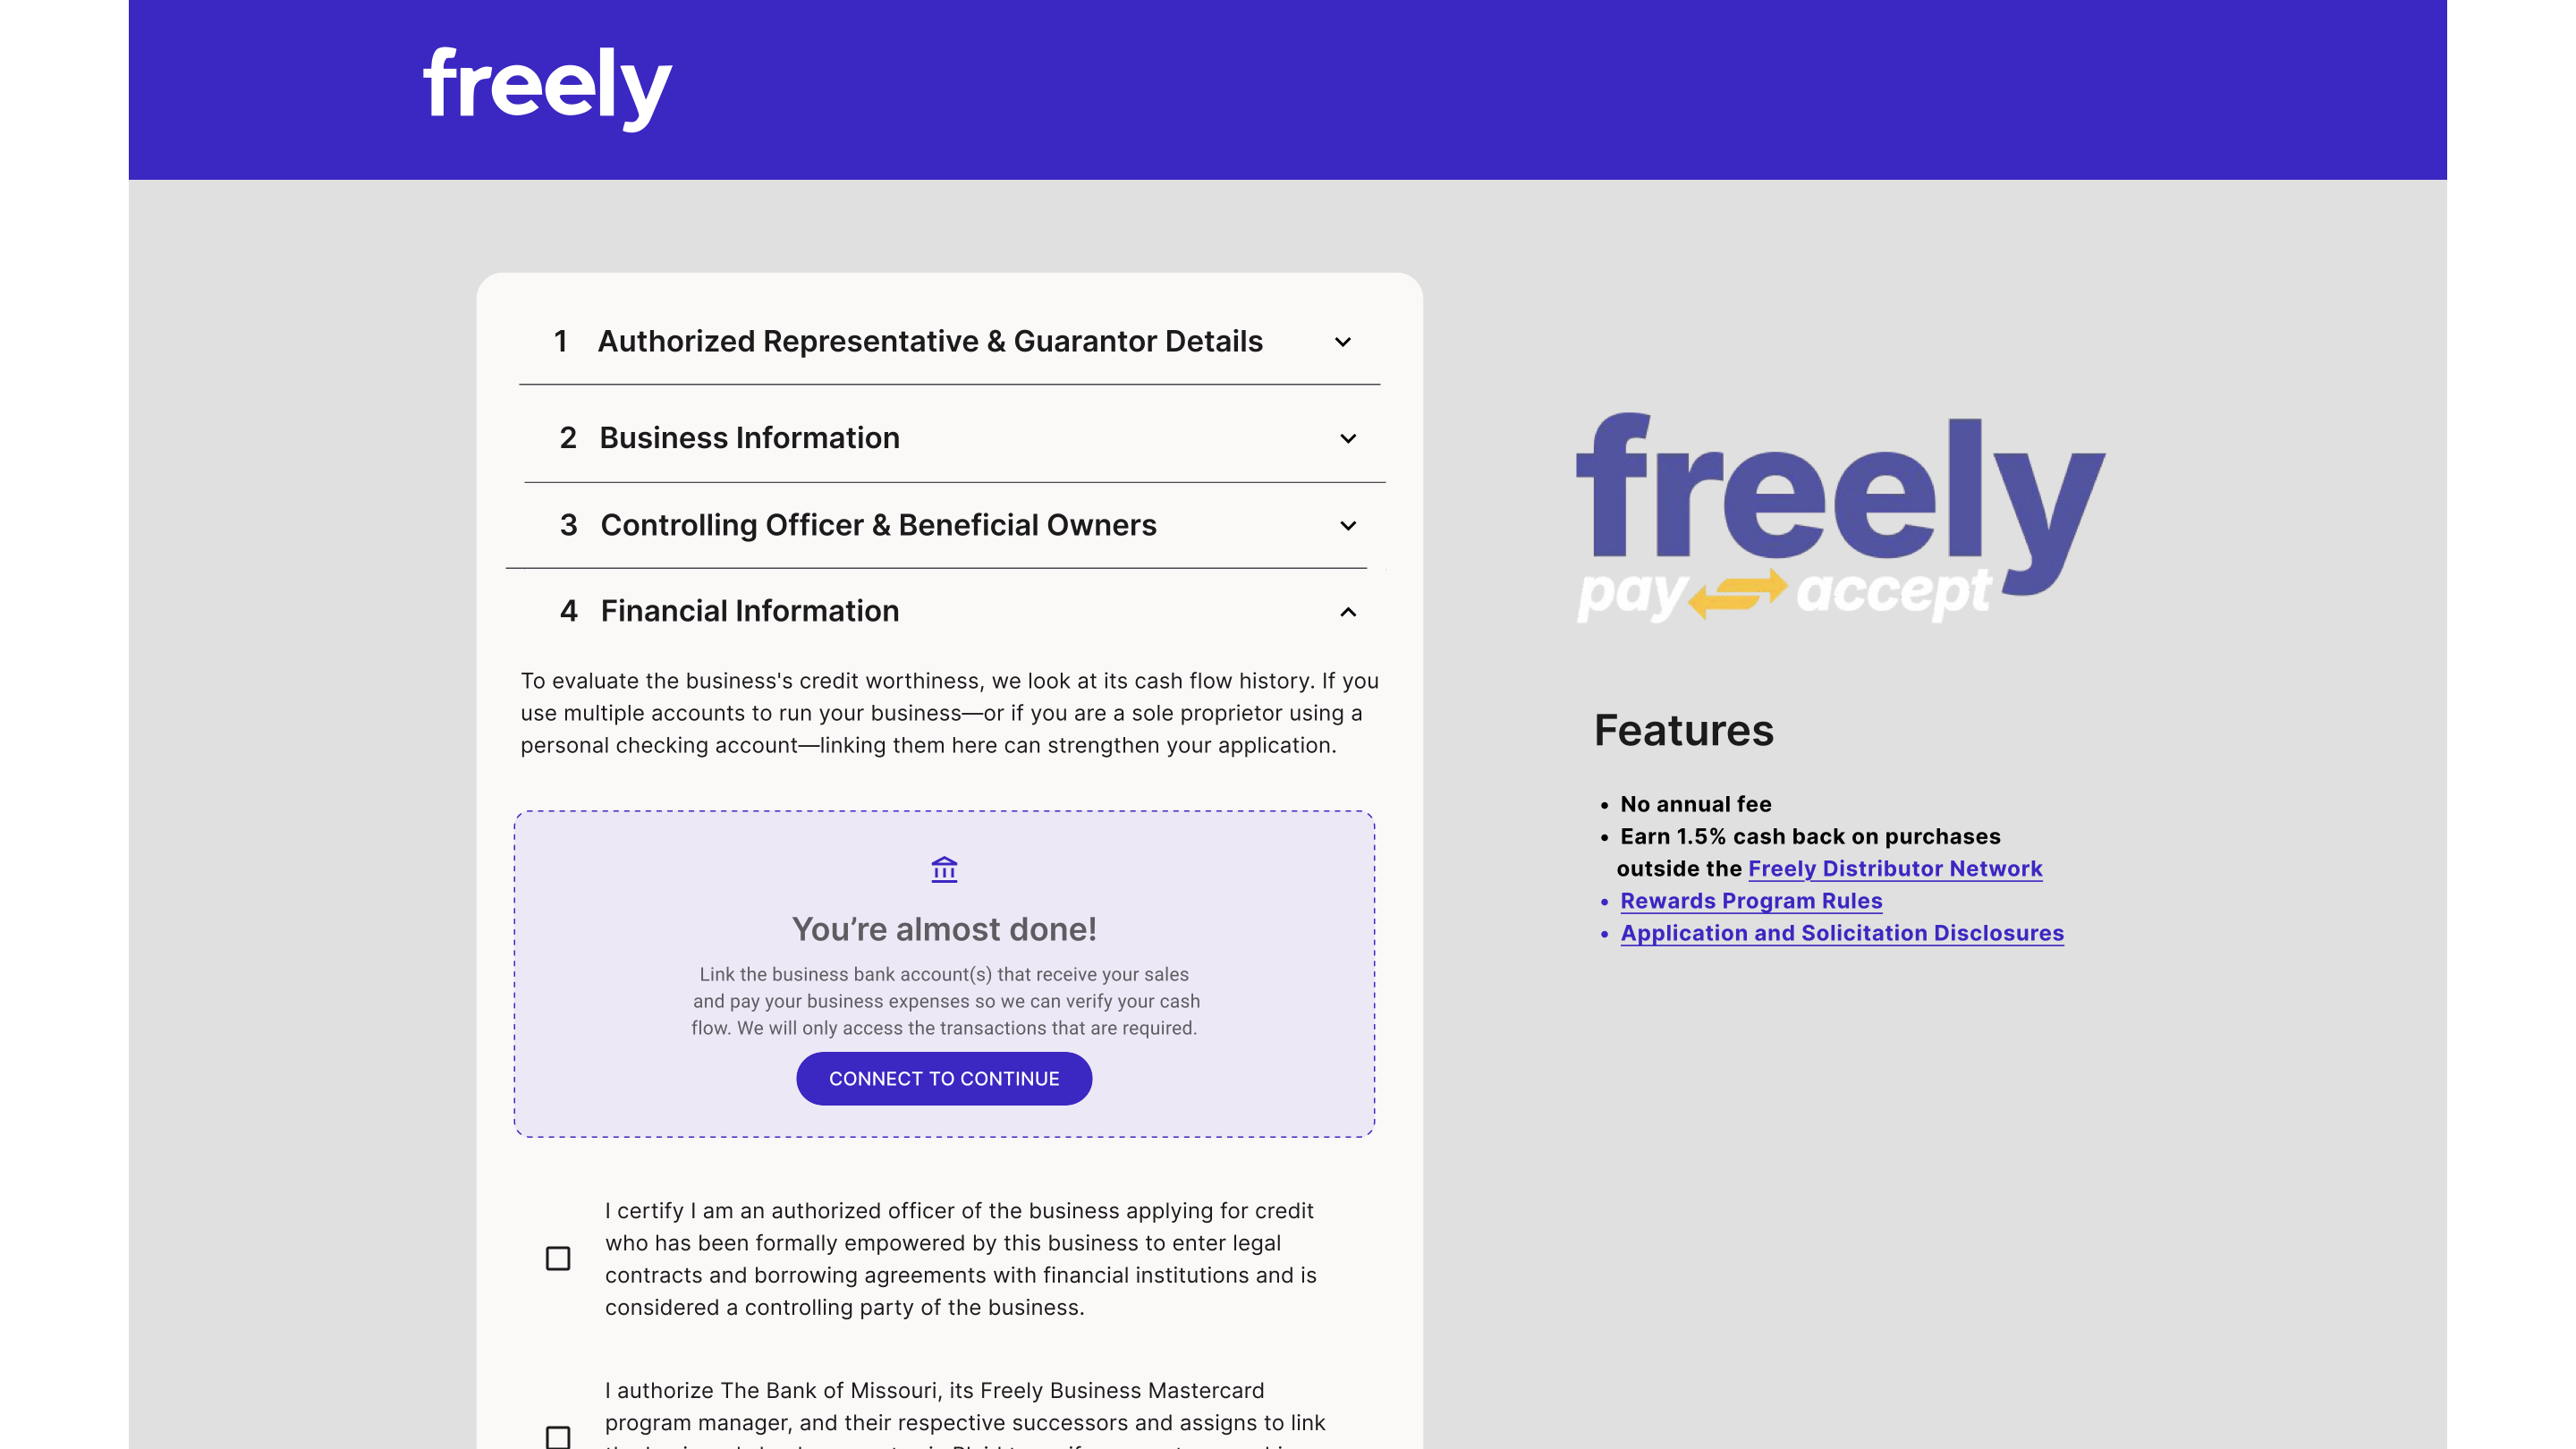
- If an applicant exits Plaid early, Step 4 doesn't throw an error or wipe the form. It reopens with a calm
"You're almost done"state and a single Connect to continue button, with all of their earlier answers saved. - Once a bank account is connected, it appears as a confirmed row (masked account number, bank name,
"Connected to Plaid") with the option to link additional accounts so Plaid Assets and Pave can evaluate their full liquidity for a higher credit limit.
6. Pre-Approval & Desktop-to-Mobile QR Handoff
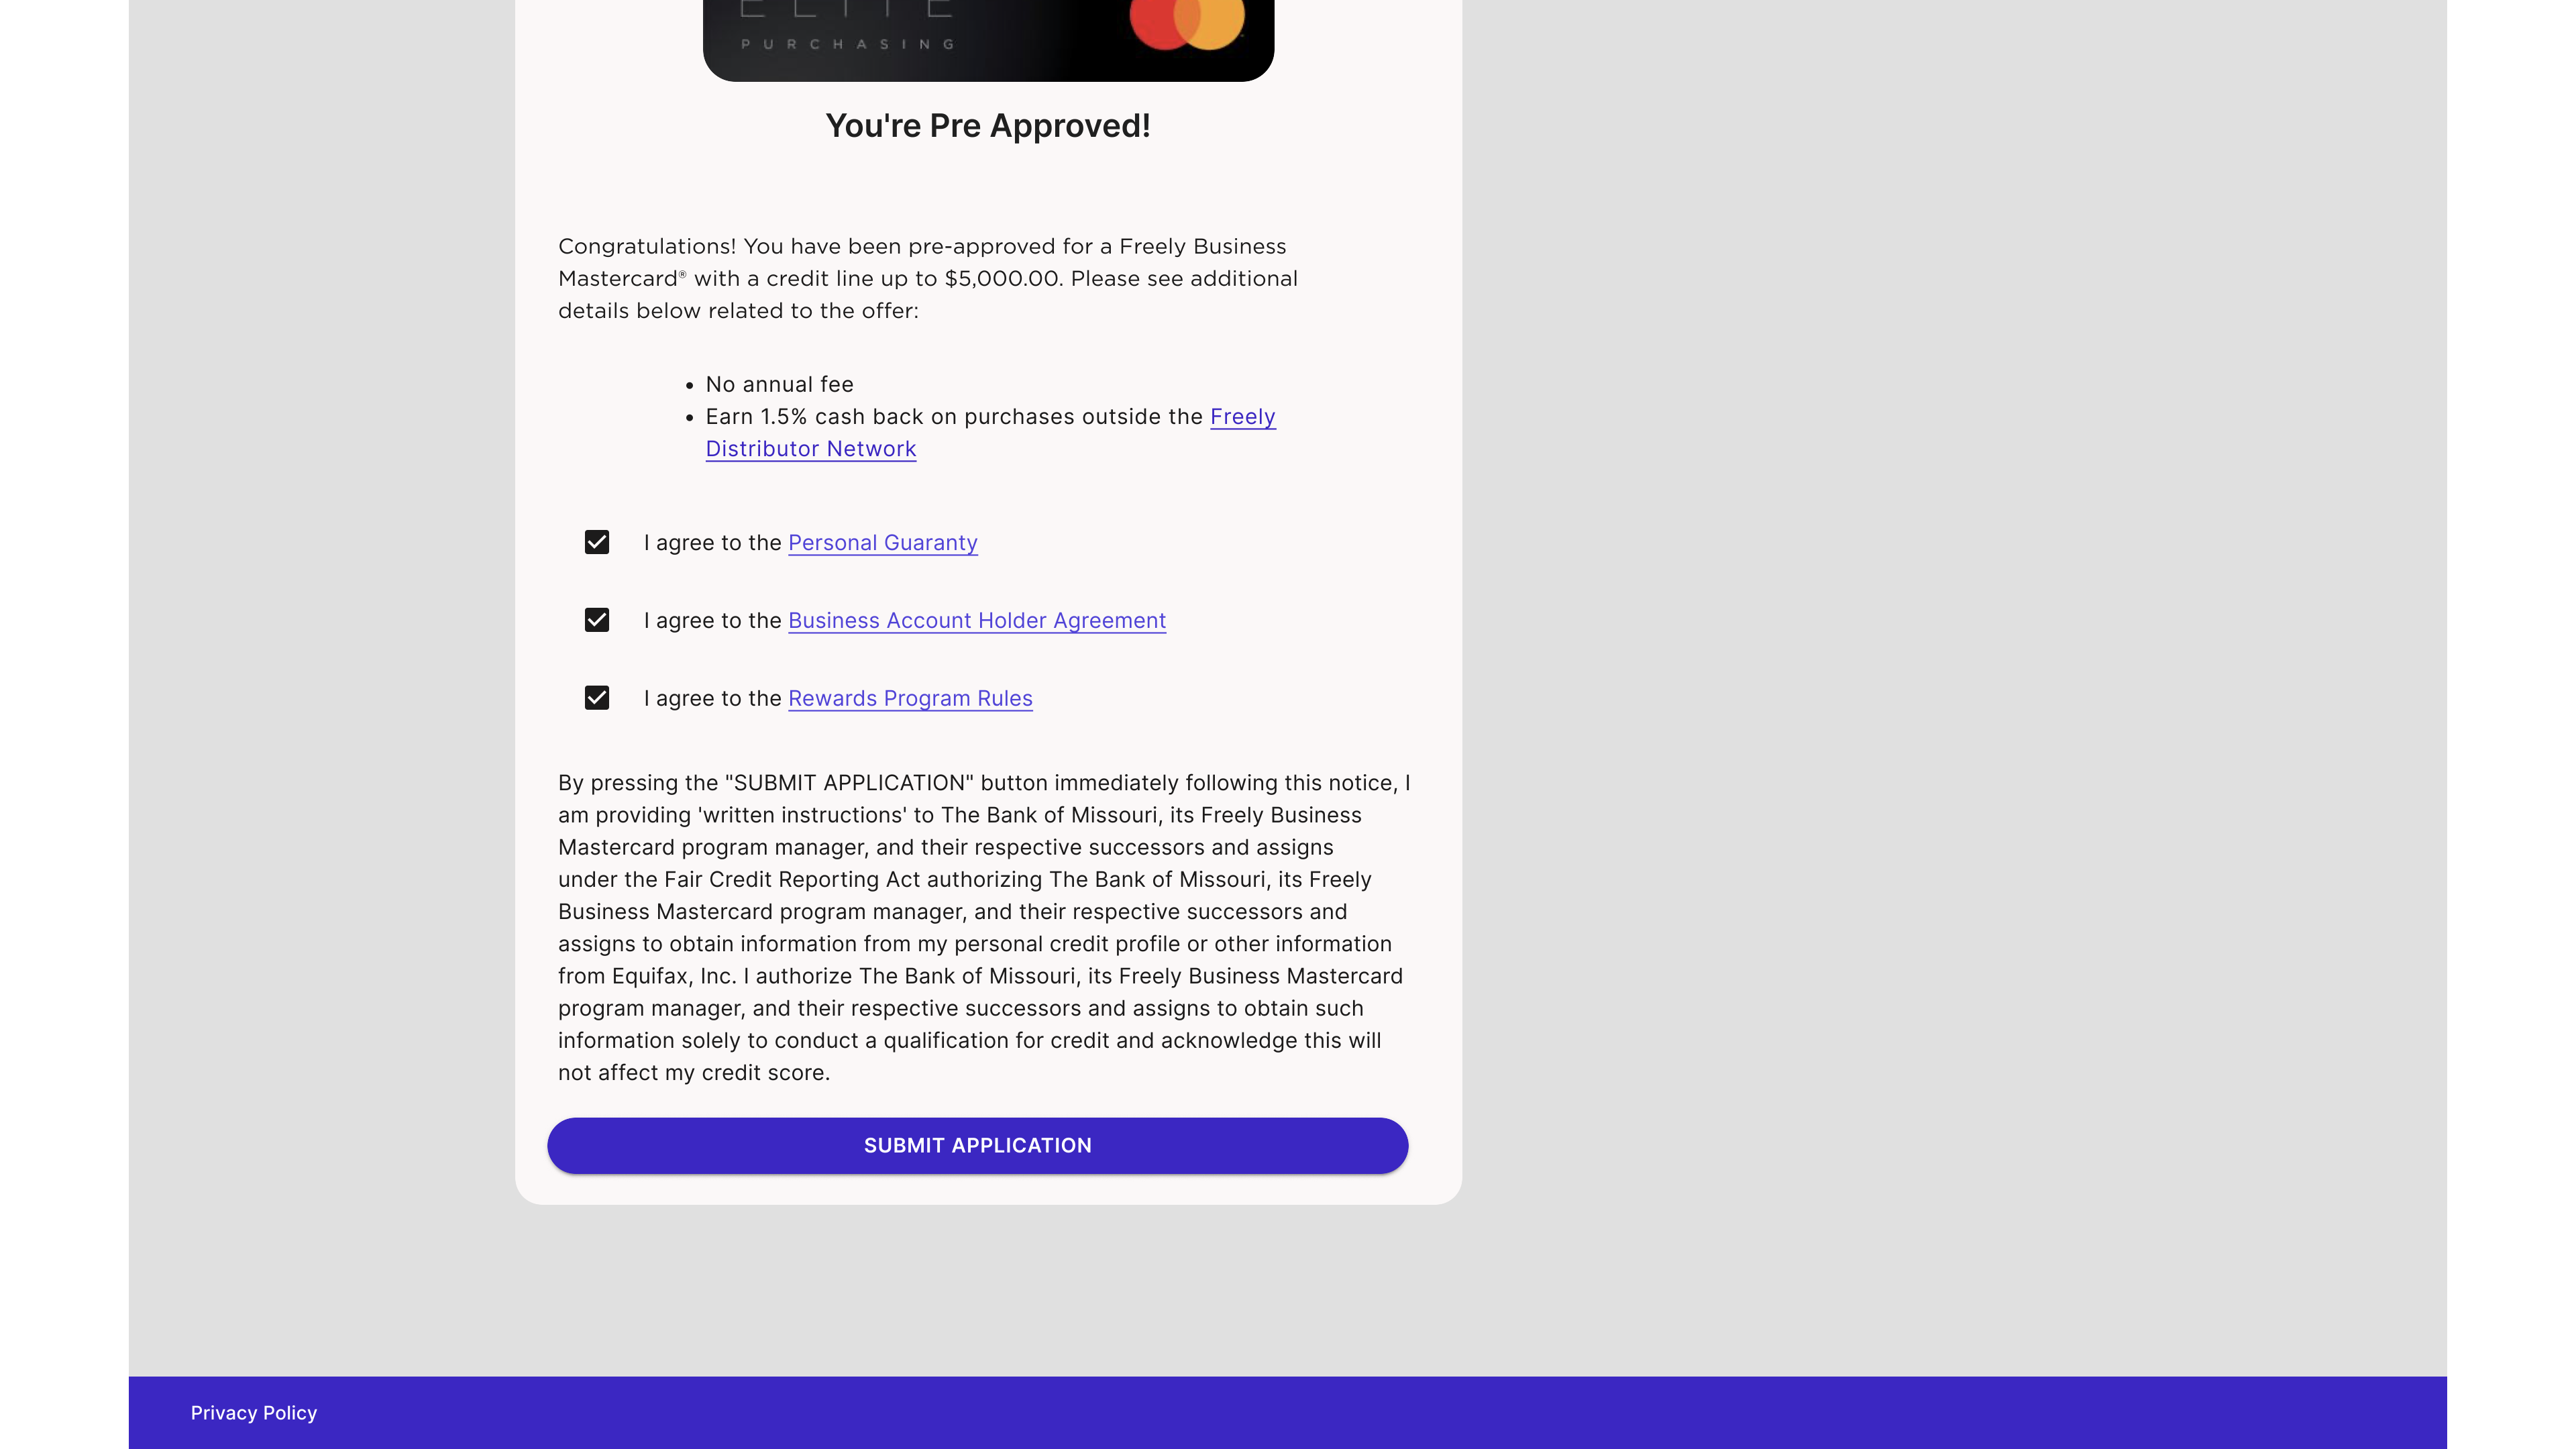
Once business verification and Plaid linking finish, the applicant gets an instant pre-approval decision:
- Inline agreement review: Business owners can read and accept the Business Card Agreement, Personal Guaranty, and rate table inline before the final credit pull.
- Desktop-to-mobile QR handoff: Since most business applications are filled out on a laptop (
78%+), the final confirmation screen shows an App Store / Google Play QR code so the owner can scan it with their phone, sign in, and add their virtual Mastercard to Apple or Google Wallet right away.
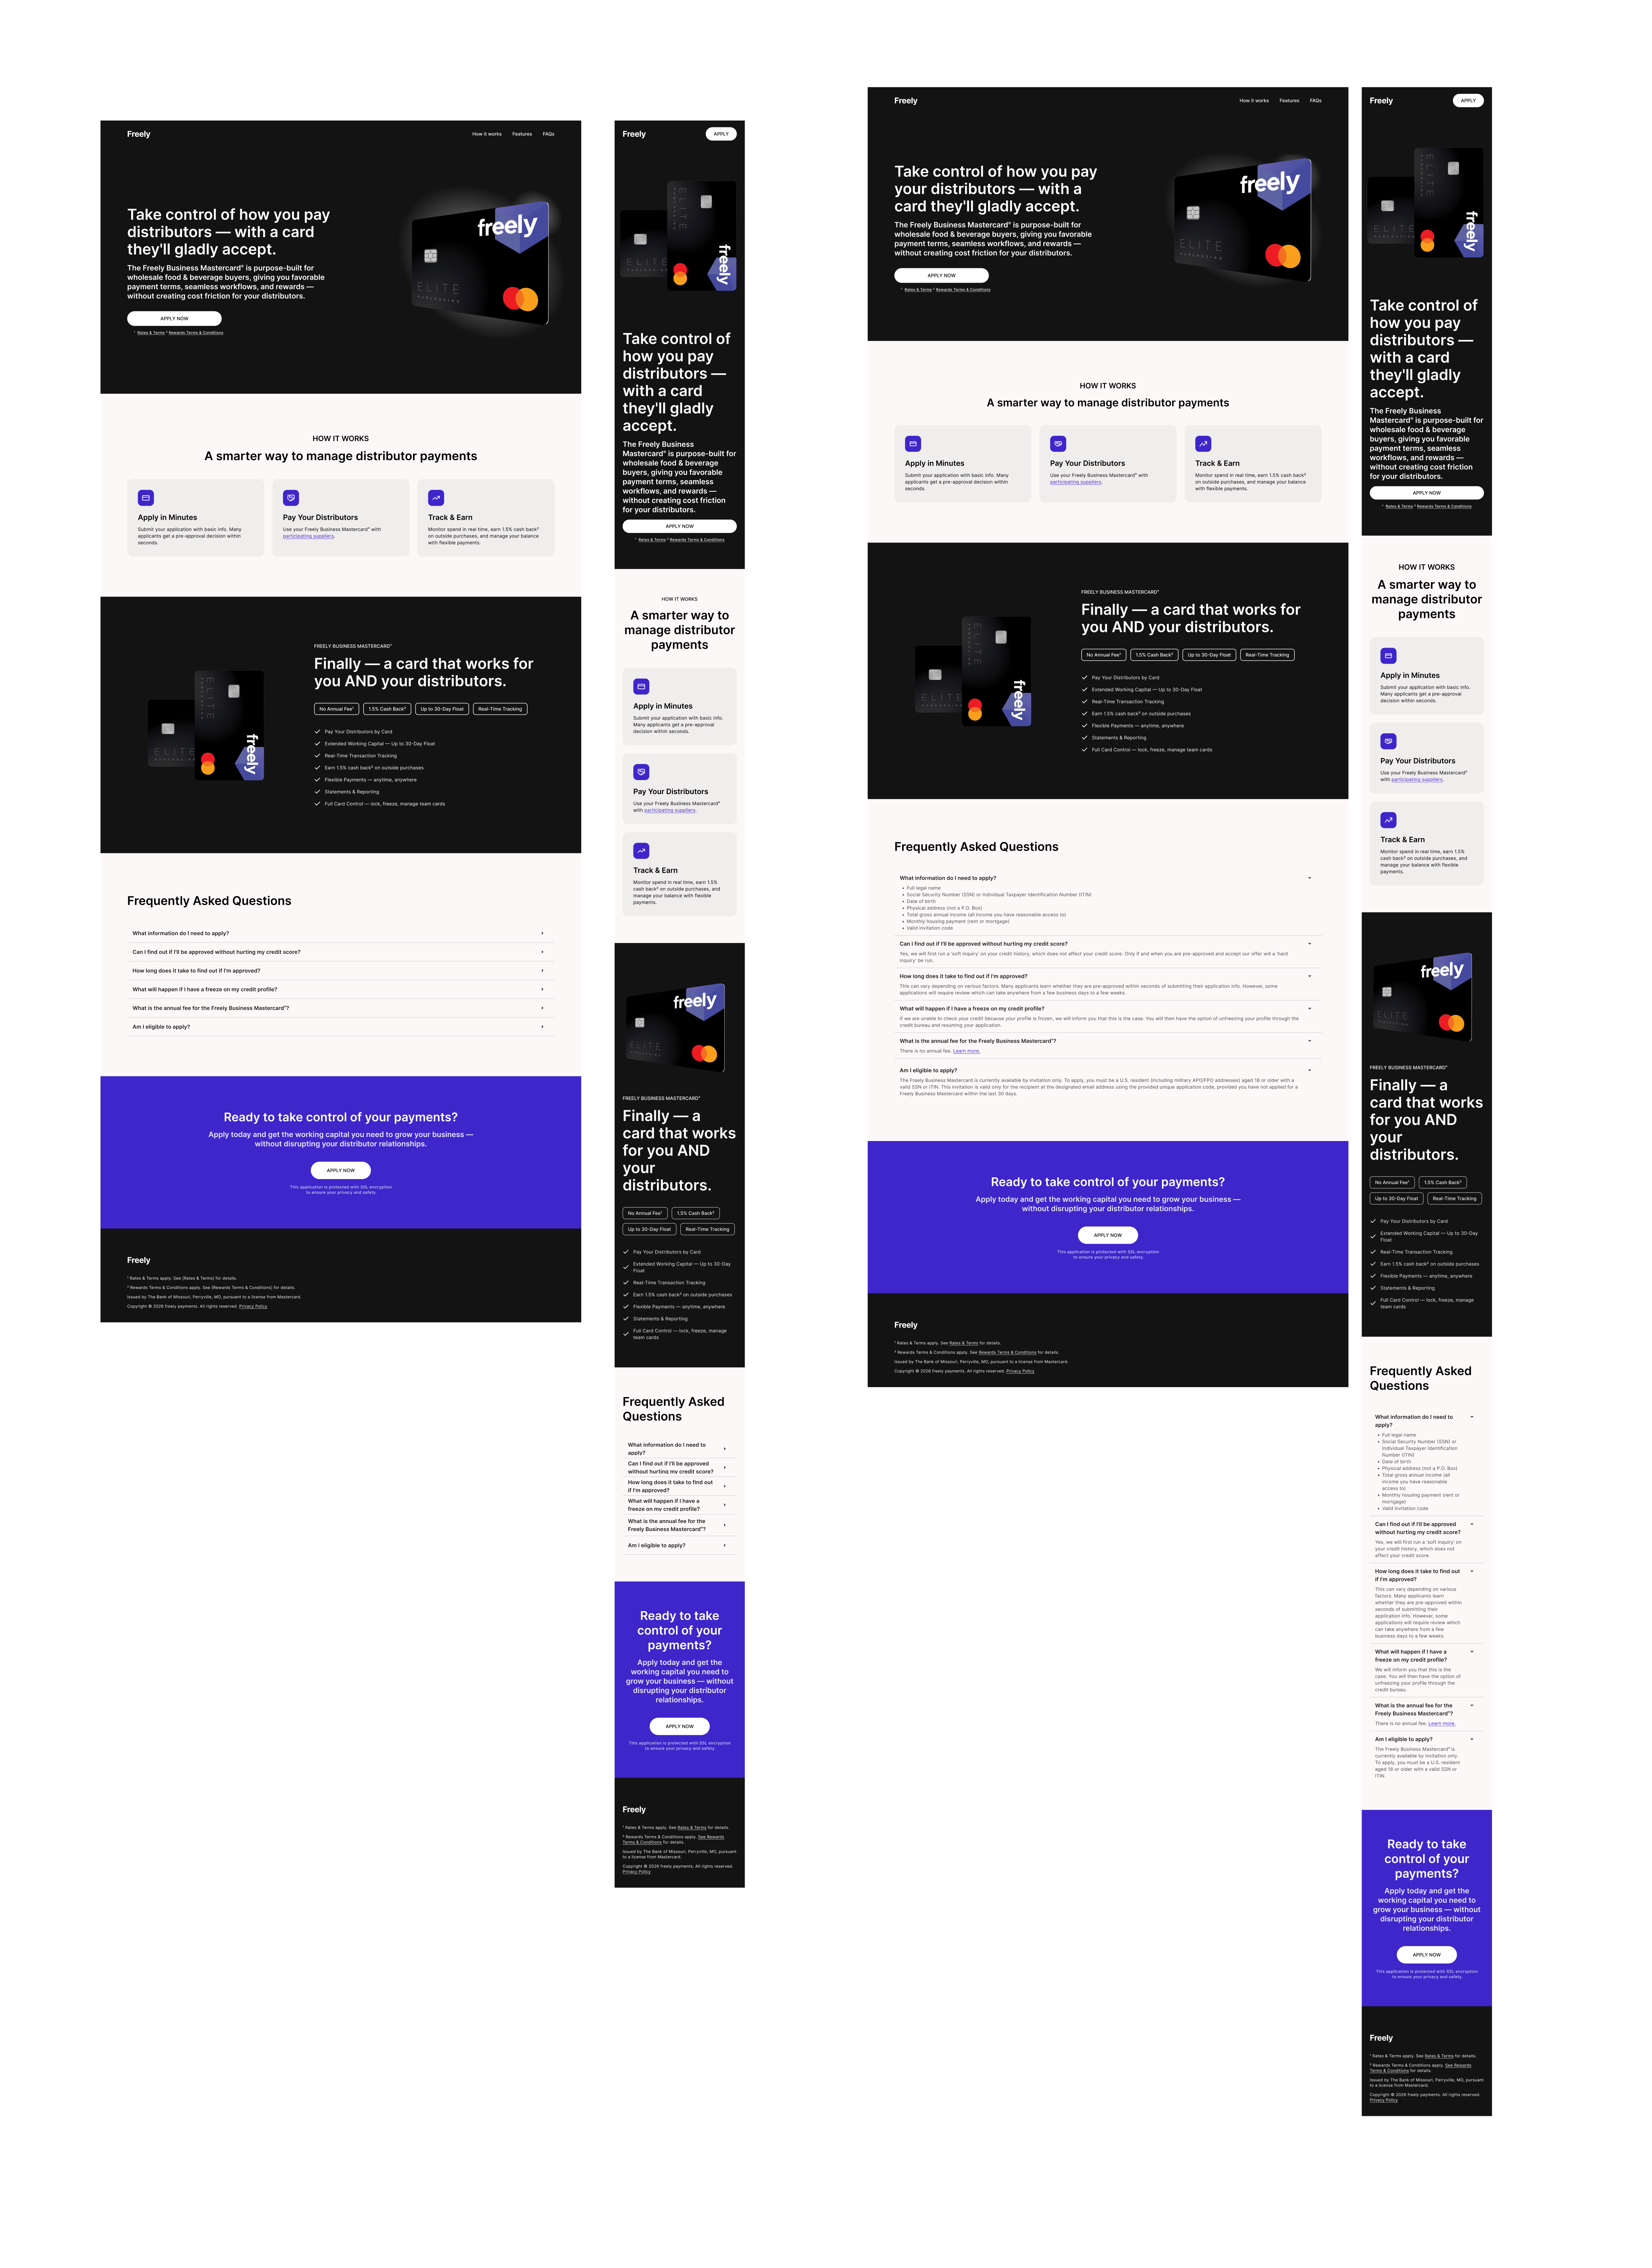
7. Marketing & Acquisition Landing Page (Light vs. Dark Explorations)
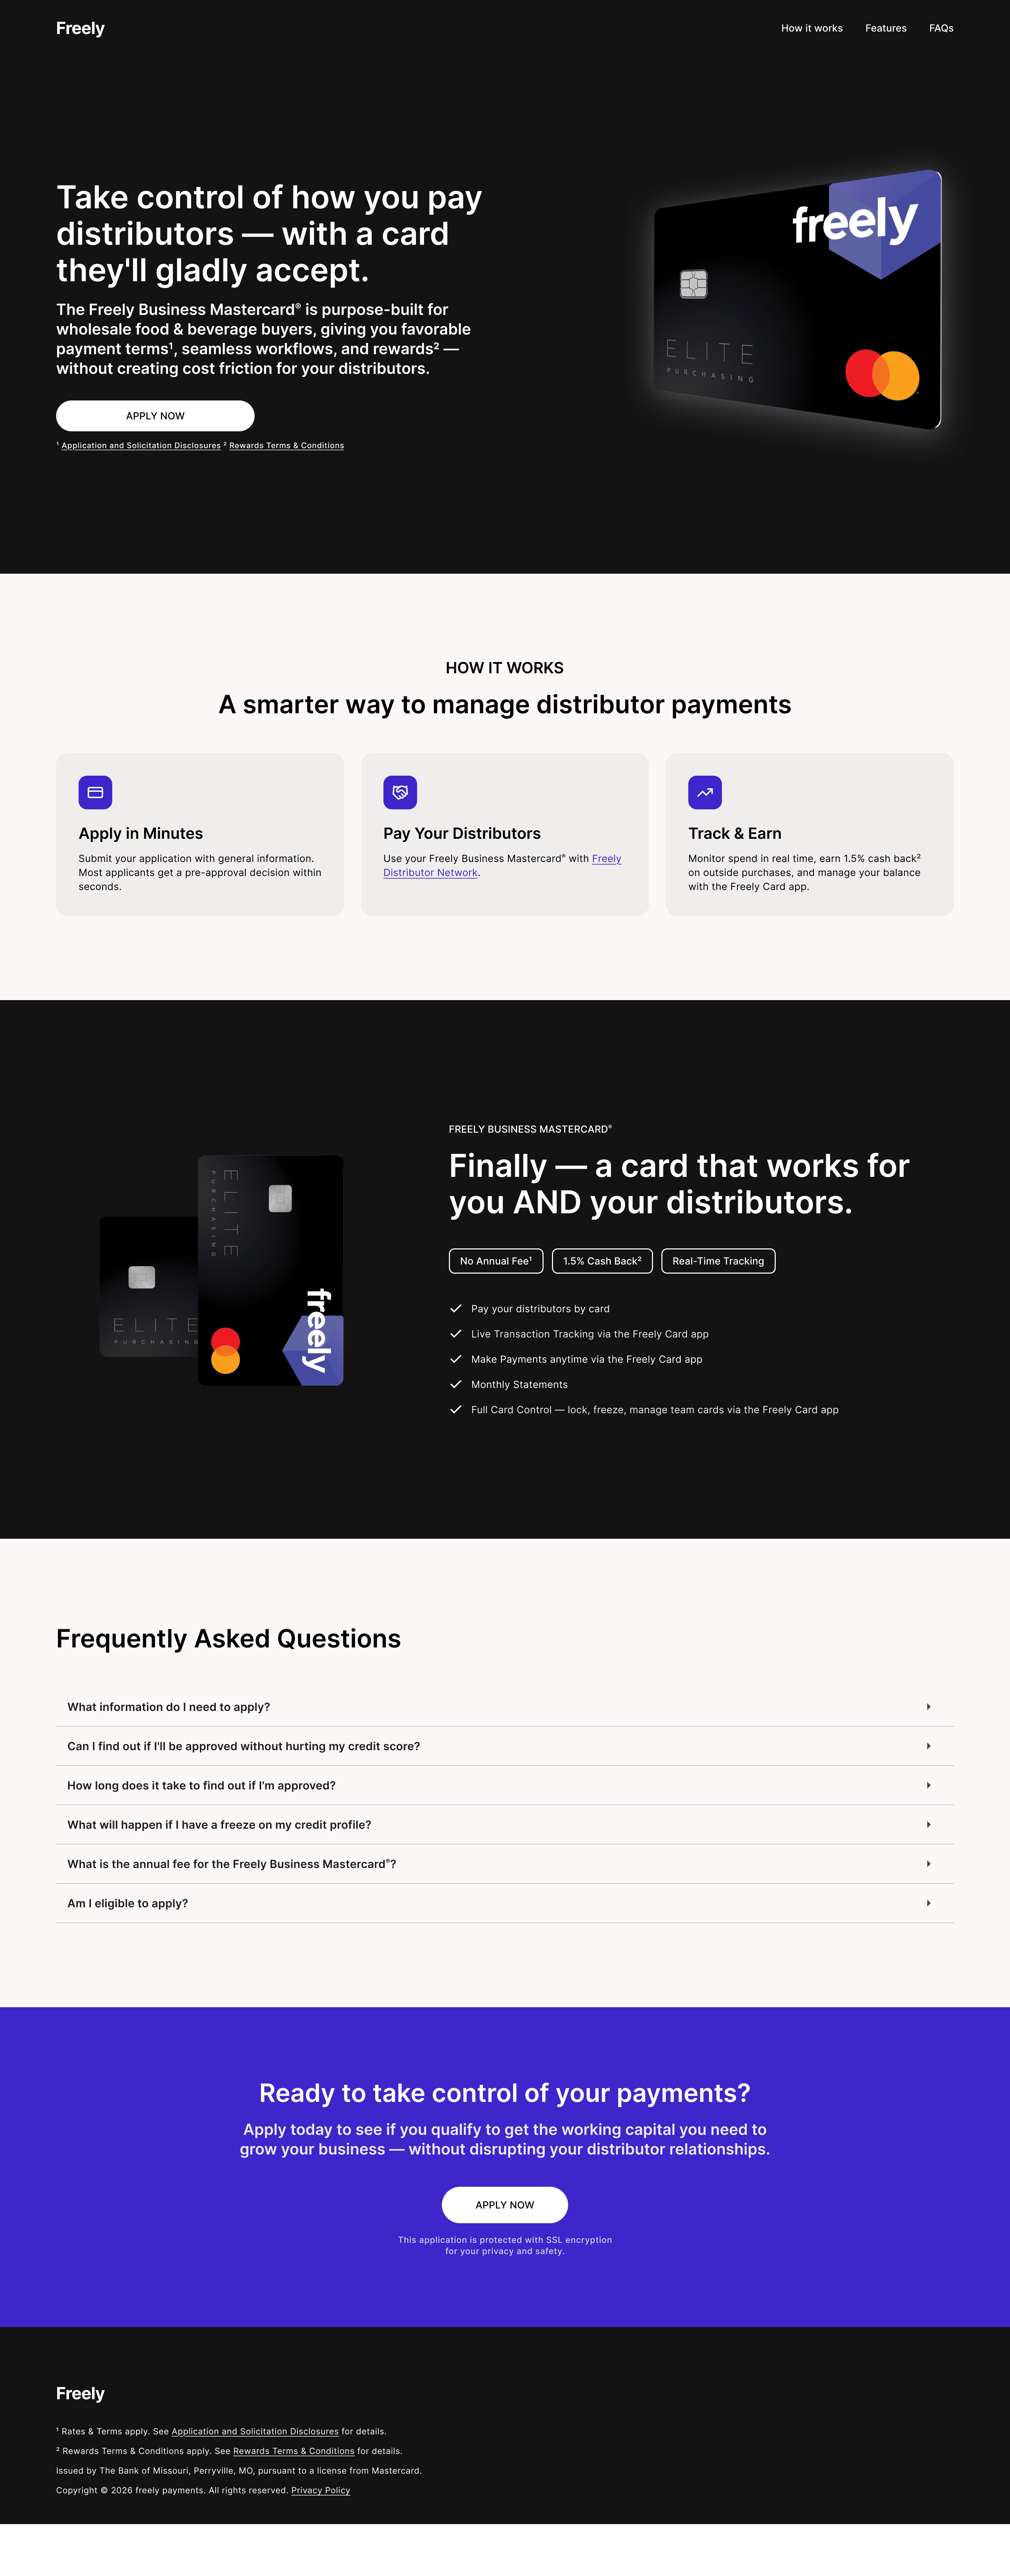
Alongside the business credit application, I designed the responsive Freely Commercial Landing Page across desktop and mobile (v1 Proposal → v3a Light → v3b Consistent Dark Version → v4 Shipped)—exploring both high-contrast dark and light art directions while breaking down 30-day float terms, 1.5% cashback on outside purchases, and soft-pull credit protection in plain language.
8. Invite-Only Soft-Launch Pilot Metrics (Feb – Oct 2026)
Freely is currently live in an invite-only commercial soft launch with initial foodservice accounts while we finalize the automated FinCEN 25%+ KYB + Plaid (Assets & Identity) → Pave → Alloy UW underwriting rollout:
| Metric | Soft-Launch Pilot Result (Feb – Oct 2026) |
|---|---|
Active Commercial Cards (Cards Outstanding) |
12 Active Corporate Cards (up from 1 card in Feb 2026) |
| Invites & Applications Submitted | 37 Invites · 18 Applications Submitted (10 Approved · 1 Pre-Approved · 0 Errors) |
| Settled Commercial Purchase Volume | $24,144.92 Total (161 Settled Purchases · $20,144.19 Peak Month) |
| In-App & Web Bill Payments | $24,639.73 Total (24 Payments · 100% Repayment Coverage) |
| Distributor Co-Brands Designed | 5 Card Designs (Freely Base, Ace Endico, M&V Provisions, Hillcrest, Vitco) |